In last month’s article titled “How to Make the Most of Digital Marketing,” we examined how digital marketing can help your business grow. Unfortunately, this involves more than waving a magic wand. You can either choose to do it yourself or hire an agency to do it for you. Either way, if it’s not well done, you could end up wasting a lot of money with no return on your investment.
Indeed, any business will want to implement a system that promises to grow revenue. But the biggest mistake is to dive into a scheme that you don’t understand well. Understanding the potential of digital marketing and how you can deploy it effectively will significantly help meet your revenue goals.
Tips to Avoid Losing Money in Digital Marketing
Here are some tips to help you effectively target your audience and eliminate wasteful spending in your digital marketing efforts:
Create a Strategy A digital marketing strategy serves as a guide to what you should and shouldn’t do. Invest in marketing that is in line with your mission and goals. And then be ready to make improvements and adjustments because the digital market is always changing.
Understand Different Platforms Each platform has its strengths and weaknesses, whether you’re looking at LinkedIn, Facebook, Google ads, etc.
Use Good Content People will easily trust the content that is engaging and adds value in some way. No matter the quality of your product or service, terrible content will cause you to lose potential customers. Always remember your content is a direct reflection of your brand.
Ads When you run ads, they will be displayed when there are searches on the internet relating to what you have advertised. This costs money. To avoid paying on unnecessary clicks or views that don’t convert to leads, run targeted ads. You can also use negative keywords, geo-targeting, or influencers. Keep in mind that any platform offering paid promotion options has as its default to spend your budget as fast as possible (they are in business, too).
Track Your Results Track your results on a daily, weekly, or monthly basis. This is the best way to know if you are wasting money. Measure and track your campaigns to understand how much you are making off any campaign. For every single $1 spent, if you are not making any returns you need to rethink your strategies. Note that it could take 60 to 90 days to get enough data for proper analysis.
Avoid Buying Fake Followers This is simply a bad idea because you will get little or no return on your investment. The fake accounts will be inactive, and hence no engagement or sales.
Test Carry out A/B testing for anything you want to put out there to your target audience. Be it content, emails, newsletters, social media posts, campaigns or ads, testing will save you from marketing with low or no returns.
Add a Call to Action What do you want an interested reader or viewer to do: make a call; fill out a form; subscribe; make a purchase; or visit a website?
Don’t Ignore Existing Customers Approximately 40 percent of business revenue is from returning customers. Specifically target this group with offers, new products or services, or just wishing them well on holidays.
Don’t Hire Bad Marketing Consultants Finally, you might decide to outsource the marketing if your business doesn’t have employees with the necessary skills, or if it’s overwhelming for your staff. Whatever the reason, don’t make the mistake of hiring bad consultants.
Avoid Wasting Money on Digital Marketing with These Tips
October 1, 2020 · Blog, What's New in Technology
⏱ 4 min read
In last month’s article titled “How to Make the Most of Digital Marketing,” we examined how digital marketing can help your business grow. Unfortunately, this involves more than waving a magic wand. You can either choose to do it yourself or hire an agency to do it for you. Either way, if it’s not well done, you could end up wasting a lot of money with no return on your investment.
Indeed, any business will want to implement a system that promises to grow revenue. But the biggest mistake is to dive into a scheme that you don’t understand well. Understanding the potential of digital marketing and how you can deploy it effectively will significantly help meet your revenue goals.
Tips to Avoid Losing Money in Digital Marketing
Here are some tips to help you effectively target your audience and eliminate wasteful spending in your digital marketing efforts:
Create a Strategy A digital marketing strategy serves as a guide to what you should and shouldn’t do. Invest in marketing that is in line with your mission and goals. And then be ready to make improvements and adjustments because the digital market is always changing.
Understand Different Platforms Each platform has its strengths and weaknesses, whether you’re looking at LinkedIn, Facebook, Google ads, etc.
Use Good Content People will easily trust the content that is engaging and adds value in some way. No matter the quality of your product or service, terrible content will cause you to lose potential customers. Always remember your content is a direct reflection of your brand.
Ads When you run ads, they will be displayed when there are searches on the internet relating to what you have advertised. This costs money. To avoid paying on unnecessary clicks or views that don’t convert to leads, run targeted ads. You can also use negative keywords, geo-targeting, or influencers. Keep in mind that any platform offering paid promotion options has as its default to spend your budget as fast as possible (they are in business, too).
Track Your Results Track your results on a daily, weekly, or monthly basis. This is the best way to know if you are wasting money. Measure and track your campaigns to understand how much you are making off any campaign. For every single $1 spent, if you are not making any returns you need to rethink your strategies. Note that it could take 60 to 90 days to get enough data for proper analysis.
Avoid Buying Fake Followers This is simply a bad idea because you will get little or no return on your investment. The fake accounts will be inactive, and hence no engagement or sales.
Test Carry out A/B testing for anything you want to put out there to your target audience. Be it content, emails, newsletters, social media posts, campaigns or ads, testing will save you from marketing with low or no returns.
Add a Call to Action What do you want an interested reader or viewer to do: make a call; fill out a form; subscribe; make a purchase; or visit a website?
Don’t Ignore Existing Customers Approximately 40 percent of business revenue is from returning customers. Specifically target this group with offers, new products or services, or just wishing them well on holidays.
Don’t Hire Bad Marketing Consultants Finally, you might decide to outsource the marketing if your business doesn’t have employees with the necessary skills, or if it’s overwhelming for your staff. Whatever the reason, don’t make the mistake of hiring bad consultants.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Due to the uncertainty of COVID-19, many schools across America have transitioned to at-home learning. This alone presents a whole new set of challenges for parents, not the least of which is figuring out what to feed your kids for lunch – every single day of the week. While peanut butter and jelly is a reliable standby, here are some cheap, easy alternatives you can whip up in no time.
English Muffin Pizza
Grab some English muffins and top them with pizza sauce or marinara. Either one will work. (Hint: use the store brand because it’s comparable and usually costs less.) If you like, you can even add shredded cheese. Put them in a toaster oven and bake. Now comes the fun part: create a face. Use olives for the nose and eyes. Cut up yellow, red, and green peppers into thin slices to form a mouth and eyebrows. For the extra peppers, use ranch dressing for dipping. This one is fun and healthy!
Lunchables Knockoff
Pre-packaged meals generally cost more. So why not create your own version of this lunch-time favorite and save some money? Buy round, butter crackers with ridges on the edge (like Ritz, but buy the store brand); round, sliced lunch meat; and small, sliced squares of cheese. Place each in the spaces in a plastic divided container. Cut up some fruit (apples, pears, anything you like) and serve. If natural sugar isn’t enough for your little ones, throw in a cookie.
Pita Pockets
You can stuff these full of anything you like. Making tuna salad for a filler is always delish but takes a bit of prep, so for time’s sake, add lunch meat. After that, add lettuce and anything else your child likes. Maybe some tomatoes or cucumbers, then add a condiment, mustard, or mayo. For a side, choose local, seasonal produce. It’s always cheaper than out-of-season choices.
Meat-Free Lunch
Purchasing meat can get expensive, so why not go veggie for a few days? Your DIY lunch kit might include cheese cubes, crackers, cherry (or grape) tomatoes, and green or purple grapes. If you get inspired, cut up apples and bananas into bite-sized portions. Throwing in some nuts for a little extra crunch is always a good idea, too. If you want to make these meals a regular thing, buy reusable, compartmentalized containers like EasyLunchBoxes, affordably priced at $14 for four. You can also buy them on Amazon. Carve out some time on a Saturday afternoon and make these in bulk to save time during your busy week. You might even ask the kids to help!
Ants on a Log
Cut up some celery (the logs). Fill with peanut butter, then sprinkle raisins on top (the ants). Serve with cheese cubes, graham crackers, yogurt, and/or fresh fruit. Kids love this one, especially because of the funny name.
Pancake Lunch
Everyone loves Saturday morning pancakes, so why not serve them for lunch, too? Here’s a thought: prepare a double batch of pancakes, plus bacon and fresh fruit on the weekend; then save half for Monday and pop them in the microwave. This way, you won’t have to prepare them twice. Don’t forget the syrup!
Cottage Cheese and Fruit
This lunch might well be the quickest of all to make. Place two scoops of cottage cheese in a leak-proof container, then add some canned fruit such as peaches, pineapple or mandarin oranges. Crackers (graham or saltines) with a little vat of peanut butter for dipping completes this easy, peasy meal.
We hope that these cost-saving lunches help save time and worry. With all that’s going on, you’ve got enough on your plate!
Due to the uncertainty of COVID-19, many schools across America have transitioned to at-home learning. This alone presents a whole new set of challenges for parents, not the least of which is figuring out what to feed your kids for lunch – every single day of the week. While peanut butter and jelly is a reliable standby, here are some cheap, easy alternatives you can whip up in no time.
English Muffin Pizza
Grab some English muffins and top them with pizza sauce or marinara. Either one will work. (Hint: use the store brand because it’s comparable and usually costs less.) If you like, you can even add shredded cheese. Put them in a toaster oven and bake. Now comes the fun part: create a face. Use olives for the nose and eyes. Cut up yellow, red, and green peppers into thin slices to form a mouth and eyebrows. For the extra peppers, use ranch dressing for dipping. This one is fun and healthy!
Lunchables Knockoff
Pre-packaged meals generally cost more. So why not create your own version of this lunch-time favorite and save some money? Buy round, butter crackers with ridges on the edge (like Ritz, but buy the store brand); round, sliced lunch meat; and small, sliced squares of cheese. Place each in the spaces in a plastic divided container. Cut up some fruit (apples, pears, anything you like) and serve. If natural sugar isn’t enough for your little ones, throw in a cookie.
Pita Pockets
You can stuff these full of anything you like. Making tuna salad for a filler is always delish but takes a bit of prep, so for time’s sake, add lunch meat. After that, add lettuce and anything else your child likes. Maybe some tomatoes or cucumbers, then add a condiment, mustard, or mayo. For a side, choose local, seasonal produce. It’s always cheaper than out-of-season choices.
Meat-Free Lunch
Purchasing meat can get expensive, so why not go veggie for a few days? Your DIY lunch kit might include cheese cubes, crackers, cherry (or grape) tomatoes, and green or purple grapes. If you get inspired, cut up apples and bananas into bite-sized portions. Throwing in some nuts for a little extra crunch is always a good idea, too. If you want to make these meals a regular thing, buy reusable, compartmentalized containers like EasyLunchBoxes, affordably priced at $14 for four. You can also buy them on Amazon. Carve out some time on a Saturday afternoon and make these in bulk to save time during your busy week. You might even ask the kids to help!
Ants on a Log
Cut up some celery (the logs). Fill with peanut butter, then sprinkle raisins on top (the ants). Serve with cheese cubes, graham crackers, yogurt, and/or fresh fruit. Kids love this one, especially because of the funny name.
Pancake Lunch
Everyone loves Saturday morning pancakes, so why not serve them for lunch, too? Here’s a thought: prepare a double batch of pancakes, plus bacon and fresh fruit on the weekend; then save half for Monday and pop them in the microwave. This way, you won’t have to prepare them twice. Don’t forget the syrup!
Cottage Cheese and Fruit
This lunch might well be the quickest of all to make. Place two scoops of cottage cheese in a leak-proof container, then add some canned fruit such as peaches, pineapple or mandarin oranges. Crackers (graham or saltines) with a little vat of peanut butter for dipping completes this easy, peasy meal.
We hope that these cost-saving lunches help save time and worry. With all that’s going on, you’ve got enough on your plate!
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
As bad as the economy is right now due to the COVID outbreak in the United States, many economists are predicting that the long-term outlook is much bleaker. Alas, Congress and the Federal Reserve’s efforts at stimulus and interest rate management have done much to keep the economy and stock market afloat. However, small businesses – the backbone of America’s employment growth – are closing every day. As consumer spending reduces further, the impact will likely affect Wall Street. Consequently, share prices may soon begin correcting to reflect the future more so than the present.
It should come as no surprise, then, that 88 percent of respondents admit they are worried about their finances, according to a recent survey conducted by the National Endowment for Financial Education.
This economic decline has presented an interesting mix of demographics who have or will be affected the most over the long term. For instance, many low-income workers have remained employed throughout the pandemic because their jobs are considered “essential services.” This includes check-out clerks at grocery stores; laborers who work outdoor jobs; nurses, orderlies, and nursing home attendants.
By contrast, many white-collar business owners – such as physicians and dentists– closed shop for a few months and/or have reduced the number of patients they see. Alas, 79 percent of those surveyed with a household income of more than $100,000 a year said they were at least somewhat concerned about their financial situation.
Millennials are the generation most likely to change the way they manage their finances in the future. Although many have remained employed in white-collar jobs – primarily due to their technology-enhanced skills and knowledge – they have reason to be concerned. After all, this generation has already lived through the market downturn following 9/11, the Great Recession, and now a historic economic decline caused by the coronavirus. In fact, once they finally got a foothold in their careers, this recent downturn obliterated the last five years’ worth of economic growth. Going forward, finance experts predict that these young adults will be more focused on stock-piling savings, buying modest homes when the real estate market corrects, and generally working on a long-term plan for financial stability.
While those strategies are mostly good, it’s a shame this generation had to learn the hard way – all while encumbered with historically unprecedented student loan debt. However, as these lessons are passed down through generations – much the way the Great Depression had a lasting impact on the Silent Generation – U.S. populations may see higher savings rates at the expense of lower GDP growth.
For households recovering from financial stress or looking to create a plan for stronger financial resiliency no matter what the future holds, consider the following strategies.
First priority: Save from three to six months’ worth of liquid, emergency funds should you encounter a large expense, such as an auto repair or a temporary loss of income.
Learn how to budget effectively, which includes examining if you overpay for basic household needs or do not know how much of your income is spent superfluously every month.
Take stock of the full scope of your financial resources, including:
Savings accounts
Investment accounts
Retirement accounts
Health savings accounts
College savings accounts
Whole life insurance
Real property
Structured settlements
Vehicles (auto, boat, motorcycle, recreational)
Art, jewelry, wine, or other high-value collectibles
Expensive furnishings and household items
Develop a Plan B to help supplement any income loss right now; a Plan C to help bolster your savings rate once you’re back to full income; and a Plan D strategy for income replacement in case you’re ever in a situation like this again.
Financial setbacks will come and go; it’s the lessons we learn from them that should have the most staying power.
Long-Term Financial Impact of COVID-19
October 1, 2020 · Blog, Financial Planning
⏱ 4 min read
As bad as the economy is right now due to the COVID outbreak in the United States, many economists are predicting that the long-term outlook is much bleaker. Alas, Congress and the Federal Reserve’s efforts at stimulus and interest rate management have done much to keep the economy and stock market afloat. However, small businesses – the backbone of America’s employment growth – are closing every day. As consumer spending reduces further, the impact will likely affect Wall Street. Consequently, share prices may soon begin correcting to reflect the future more so than the present.
It should come as no surprise, then, that 88 percent of respondents admit they are worried about their finances, according to a recent survey conducted by the National Endowment for Financial Education.
This economic decline has presented an interesting mix of demographics who have or will be affected the most over the long term. For instance, many low-income workers have remained employed throughout the pandemic because their jobs are considered “essential services.” This includes check-out clerks at grocery stores; laborers who work outdoor jobs; nurses, orderlies, and nursing home attendants.
By contrast, many white-collar business owners – such as physicians and dentists– closed shop for a few months and/or have reduced the number of patients they see. Alas, 79 percent of those surveyed with a household income of more than $100,000 a year said they were at least somewhat concerned about their financial situation.
Millennials are the generation most likely to change the way they manage their finances in the future. Although many have remained employed in white-collar jobs – primarily due to their technology-enhanced skills and knowledge – they have reason to be concerned. After all, this generation has already lived through the market downturn following 9/11, the Great Recession, and now a historic economic decline caused by the coronavirus. In fact, once they finally got a foothold in their careers, this recent downturn obliterated the last five years’ worth of economic growth. Going forward, finance experts predict that these young adults will be more focused on stock-piling savings, buying modest homes when the real estate market corrects, and generally working on a long-term plan for financial stability.
While those strategies are mostly good, it’s a shame this generation had to learn the hard way – all while encumbered with historically unprecedented student loan debt. However, as these lessons are passed down through generations – much the way the Great Depression had a lasting impact on the Silent Generation – U.S. populations may see higher savings rates at the expense of lower GDP growth.
For households recovering from financial stress or looking to create a plan for stronger financial resiliency no matter what the future holds, consider the following strategies.
First priority: Save from three to six months’ worth of liquid, emergency funds should you encounter a large expense, such as an auto repair or a temporary loss of income.
Learn how to budget effectively, which includes examining if you overpay for basic household needs or do not know how much of your income is spent superfluously every month.
Take stock of the full scope of your financial resources, including:
Savings accounts
Investment accounts
Retirement accounts
Health savings accounts
College savings accounts
Whole life insurance
Real property
Structured settlements
Vehicles (auto, boat, motorcycle, recreational)
Art, jewelry, wine, or other high-value collectibles
Expensive furnishings and household items
Develop a Plan B to help supplement any income loss right now; a Plan C to help bolster your savings rate once you’re back to full income; and a Plan D strategy for income replacement in case you’re ever in a situation like this again.
Financial setbacks will come and go; it’s the lessons we learn from them that should have the most staying power.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
If you’re anxious about sending your children back to school, you’re not alone. In fact, a recent poll from ABC News/Ipsos showed that 45 percent of parents don’t want their kids in the classroom at all. But whether your kids are in school or learning at home, there’s still plenty of worry to go around. How do you cope? Here are a few suggestions from a variety of counselors and mental health professionals that can help.
Express Your Feelings
Noticing the anxiety that’s going on inside is half the battle – then let it out. “I would encourage parents to share this feeling with their partners or other family and friends,” says Michael Consuelos, MD, a senior medical advisor with the mental health management platform NeuroFlow in Philadelphia. Simply releasing what you’re feeling can often take the power of it.
Teach Your Kids How to Navigate
This starts with talking to your kids about what social distancing is, what it looks like, and how to wash their hands thoroughly. Fran Walfish, PsyD, MFT, and a family and relationship psychotherapist in Beverly Hills, Calif., suggests making up real-life situations and getting your kids to “think in advance about what they would say or do to protect themselves while preserving a friendship.” For instance, a friend of your son stands too close to him and asks to borrow a ruler. How should he react? Or your daughter is eating lunch and a friend reaches in and takes a few chips from her Doritos bag. What should she do? You can probably come up with many other scenarios that help your kids figure out the best options for keeping safe.
Have Honest Conversations
Kathleen Rivera, MD, a psychiatrist who specializes in children and adolescents at Nuvance Health in Danbury, Conn., strongly suggests talking with your kids about the situation, no matter how young they are, and asking them how they’re feeling about the changes in their school environment. What things about school do you miss the most? How is this new learning set-up working for you? What are things you don’t miss about school? Claudia Kohner, Ph.D., a licensed psychologist and creator of IntroDUCKtion to Very, Very Big Feelings app, says that if you have very young children, give them some colored pencils and a coloring book. Sit down with them and help them create a homemade book that describes the changes in their school setting and reflects their feelings that go along with it. Encouraging imaginative play with dolls and stuffed animals is also a great way to help your kids express what they’re going through.
Practice Self-Care
In these uncertain times, it’s more important than ever to be kind to yourself – and not judge yourself for failing to cross everything off your to-do list. “You don’t have to do it all,” says Elizabeth Derickson, MSW, LCSW, RPT, a therapist with online therapy provider Talkspace. This is her No. 1 piece of advice for parents who are dealing with back-to-school anxiety. She suggests setting up realistic expectations and acknowledging that there will be both good days and bad days, and allowing yourself “to learn from the bad days, move on and rock those good days.”
Embrace Change
In a few months, the landscape of your life might look radically different than it does today. That’s why being able to adapt to whatever new circumstance presents itself is key. According to Dr. Rivera, “Flexibility is the most important thing in this whole process.” Knowing you have every right to reverse your decisions is OK – and empowering.
Despite the seemingly never-ending stream of worries that inevitably crop up in our new abnormal, remember: the most constant thing in life is change. Things will get better.
If you’re anxious about sending your children back to school, you’re not alone. In fact, a recent poll from ABC News/Ipsos showed that 45 percent of parents don’t want their kids in the classroom at all. But whether your kids are in school or learning at home, there’s still plenty of worry to go around. How do you cope? Here are a few suggestions from a variety of counselors and mental health professionals that can help.
Express Your Feelings
Noticing the anxiety that’s going on inside is half the battle – then let it out. “I would encourage parents to share this feeling with their partners or other family and friends,” says Michael Consuelos, MD, a senior medical advisor with the mental health management platform NeuroFlow in Philadelphia. Simply releasing what you’re feeling can often take the power of it.
Teach Your Kids How to Navigate
This starts with talking to your kids about what social distancing is, what it looks like, and how to wash their hands thoroughly. Fran Walfish, PsyD, MFT, and a family and relationship psychotherapist in Beverly Hills, Calif., suggests making up real-life situations and getting your kids to “think in advance about what they would say or do to protect themselves while preserving a friendship.” For instance, a friend of your son stands too close to him and asks to borrow a ruler. How should he react? Or your daughter is eating lunch and a friend reaches in and takes a few chips from her Doritos bag. What should she do? You can probably come up with many other scenarios that help your kids figure out the best options for keeping safe.
Have Honest Conversations
Kathleen Rivera, MD, a psychiatrist who specializes in children and adolescents at Nuvance Health in Danbury, Conn., strongly suggests talking with your kids about the situation, no matter how young they are, and asking them how they’re feeling about the changes in their school environment. What things about school do you miss the most? How is this new learning set-up working for you? What are things you don’t miss about school? Claudia Kohner, Ph.D., a licensed psychologist and creator of IntroDUCKtion to Very, Very Big Feelings app, says that if you have very young children, give them some colored pencils and a coloring book. Sit down with them and help them create a homemade book that describes the changes in their school setting and reflects their feelings that go along with it. Encouraging imaginative play with dolls and stuffed animals is also a great way to help your kids express what they’re going through.
Practice Self-Care
In these uncertain times, it’s more important than ever to be kind to yourself – and not judge yourself for failing to cross everything off your to-do list. “You don’t have to do it all,” says Elizabeth Derickson, MSW, LCSW, RPT, a therapist with online therapy provider Talkspace. This is her No. 1 piece of advice for parents who are dealing with back-to-school anxiety. She suggests setting up realistic expectations and acknowledging that there will be both good days and bad days, and allowing yourself “to learn from the bad days, move on and rock those good days.”
Embrace Change
In a few months, the landscape of your life might look radically different than it does today. That’s why being able to adapt to whatever new circumstance presents itself is key. According to Dr. Rivera, “Flexibility is the most important thing in this whole process.” Knowing you have every right to reverse your decisions is OK – and empowering.
Despite the seemingly never-ending stream of worries that inevitably crop up in our new abnormal, remember: the most constant thing in life is change. Things will get better.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
A bill to amend the Servicemembers Civil Relief Act to extend lease protections for servicemembers under stop movement orders in response to a local, national, or global emergency, and for other purposes (S 3637) – This bill extends the Servicemembers Civil Relief Act to protect service members who were previously issued orders to change duty stations but had those orders rescinded because of the pandemic. A stop movement order may leave them with a housing and/or car lease in two different locations. This extension allows families who are unable to relocate due to pandemic-related travel restrictions to be released without penalty from their leases. It is retroactive to March 1, 2020. The bill was introduced by Sen. Jon Tester (D-MT) on May 6. It was passed by the Senate in June, the House in July, and was signed by the President on Aug. 14.
Safeguarding America’s First Responders Act of 2020 (S 3607) – This bill was introduced by Sen. Chuck Grassley (R-IA) on May 5. The bill extends death and disability benefits under the Public Safety Officers’ Benefits Program (PSOB) to public safety officers (e.g., law enforcement officers) and survivors of public safety officers who die or become injured as a result of COVID-19. The bill classifies COVID-19 or related complications suffered by a public safety officer as a personal injury sustained in the line of duty. The Act was passed in the Senate in May and in the House in July. It was signed into law on Aug. 14.
Veteran Treatment Court Coordination Act of 2019 (HR 886) – Introduced by Rep. Charlie Christ (D-FL) on Jan. 30, 2019, this legislation directs the Department of Justice to establish a Veterans Treatment Court Program to provide grants and technical assistance for state, local and tribal governments to develop and maintain veterans’ treatment courts. Treatment courts are designed to assist justice-involved vets with treatment needs such as substance abuse, mental health, and other issues unique to active service. The Act was enacted after being signed by the President on Aug. 8.
Ryan Kules and Paul Benne Specially Adaptive Housing Improvement Act of 2019 (HR 3504) – This bill is designed to amend Title 38 of the United States Code that provides for improvements to the specially adapted housing and educational assistance programs of the Department of Veterans Affairs. It is designed to help eligible disabled veterans purchase adaptive homes or upgrade existing homes to meet their specific needs for daily living activities. The bill was introduced by Rep. Gus Bilirakis (R-FL) on June 26, 2019. It was passed in the House in July 2019; in the Senate in March 2020, and was signed into law by the President on Aug. 8.
Great American Outdoors Act (HR 1957) – This Act was initially sponsored by Rep. John Lewis (D-GA) on March 28, 2019. This legislation establishes the National Parks and Public Land Legacy Restoration Fund, which is designed to support deferred maintenance projects on federal lands for fiscal years 2021 to 2025. The bill makes funding for the Land and Water Conservation Fund permanent and allocates money equal to 50 percent of energy development revenues from oil, gas, coal, or alternative or renewable energy development on federal lands and waters. The bill establishes reporting procedures for all associated projects and mandates that deposited amounts must not exceed $1.9 billion for any fiscal year. The bill was signed into law by the President on Aug. 4.
Commission on the Social Status of Black Men and Boys Act (S 2163) – Sen. Marco Rubio (R-FL) introduced this legislation on July 18, 2019. It is designed to establish a Commission on the Social Status of Black Men and Boys within the U.S. Commission on Civil Rights Office to conduct a systematic study of the conditions affecting black men and boys. The Act was passed by the Senate in June, the House in July, and was signed into law by the President on Aug. 14.
Laws to Enhance Benefits for Service Members, First Responders, Veterans and to Restore National Parks and Public Lands
September 1, 2020 · Blog, Congress at Work
⏱ 4 min read
A bill to amend the Servicemembers Civil Relief Act to extend lease protections for servicemembers under stop movement orders in response to a local, national, or global emergency, and for other purposes (S 3637) – This bill extends the Servicemembers Civil Relief Act to protect service members who were previously issued orders to change duty stations but had those orders rescinded because of the pandemic. A stop movement order may leave them with a housing and/or car lease in two different locations. This extension allows families who are unable to relocate due to pandemic-related travel restrictions to be released without penalty from their leases. It is retroactive to March 1, 2020. The bill was introduced by Sen. Jon Tester (D-MT) on May 6. It was passed by the Senate in June, the House in July, and was signed by the President on Aug. 14.
Safeguarding America’s First Responders Act of 2020 (S 3607) – This bill was introduced by Sen. Chuck Grassley (R-IA) on May 5. The bill extends death and disability benefits under the Public Safety Officers’ Benefits Program (PSOB) to public safety officers (e.g., law enforcement officers) and survivors of public safety officers who die or become injured as a result of COVID-19. The bill classifies COVID-19 or related complications suffered by a public safety officer as a personal injury sustained in the line of duty. The Act was passed in the Senate in May and in the House in July. It was signed into law on Aug. 14.
Veteran Treatment Court Coordination Act of 2019 (HR 886) – Introduced by Rep. Charlie Christ (D-FL) on Jan. 30, 2019, this legislation directs the Department of Justice to establish a Veterans Treatment Court Program to provide grants and technical assistance for state, local and tribal governments to develop and maintain veterans’ treatment courts. Treatment courts are designed to assist justice-involved vets with treatment needs such as substance abuse, mental health, and other issues unique to active service. The Act was enacted after being signed by the President on Aug. 8.
Ryan Kules and Paul Benne Specially Adaptive Housing Improvement Act of 2019 (HR 3504) – This bill is designed to amend Title 38 of the United States Code that provides for improvements to the specially adapted housing and educational assistance programs of the Department of Veterans Affairs. It is designed to help eligible disabled veterans purchase adaptive homes or upgrade existing homes to meet their specific needs for daily living activities. The bill was introduced by Rep. Gus Bilirakis (R-FL) on June 26, 2019. It was passed in the House in July 2019; in the Senate in March 2020, and was signed into law by the President on Aug. 8.
Great American Outdoors Act (HR 1957) – This Act was initially sponsored by Rep. John Lewis (D-GA) on March 28, 2019. This legislation establishes the National Parks and Public Land Legacy Restoration Fund, which is designed to support deferred maintenance projects on federal lands for fiscal years 2021 to 2025. The bill makes funding for the Land and Water Conservation Fund permanent and allocates money equal to 50 percent of energy development revenues from oil, gas, coal, or alternative or renewable energy development on federal lands and waters. The bill establishes reporting procedures for all associated projects and mandates that deposited amounts must not exceed $1.9 billion for any fiscal year. The bill was signed into law by the President on Aug. 4.
Commission on the Social Status of Black Men and Boys Act (S 2163) – Sen. Marco Rubio (R-FL) introduced this legislation on July 18, 2019. It is designed to establish a Commission on the Social Status of Black Men and Boys within the U.S. Commission on Civil Rights Office to conduct a systematic study of the conditions affecting black men and boys. The Act was passed by the Senate in June, the House in July, and was signed into law by the President on Aug. 14.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The stock market continues to perform with relative resilience, despite the current economic decline. But to be clear, without 100 percent participation in the economy – in terms of small business job creation, consumer spending, and company growth and expansion – the stock market is apt to reposition prices to reflect slower growth. With no containment or control of the pandemic on the horizon, there is plenty of uncertainty associated with future financial planning.
Anyone looking to retire in the next 10 years or so may want to take a fresh look at their current retirement income plan. In fact, they might need a Plan A, B, and C in order to stay flexible – with C being the option to continue working longer. The following are portfolio tips to consider for a 10-year time frame until retirement.
Emergency Fund
If there was one financial tip worth following pre-pandemic, it was to have liquid cash savings of six months to a year’s worth of expenses available. Workers who did are probably pretty relieved about now if they lost their job or had hours reduced. Having substantial cash available can save you from raiding retirement accounts and/or your investment portfolio.
In preparation for retirement, that cash buffer is even more important. Some advisors recommend a liquid savings fund to cover one to three years’ worth of expenses. That’s because once you’re on a fixed income, you’re not likely to replenish that account. What it can do is supplement variable retirement income that is reliant on the markets. Having a cash buffer gives investments time to recover from temporary losses so you don’t have to plunder your principal.
Status of Social Security
While you may know what your benefit level is for retirement at a certain date, be aware that your benefit could change – even after you’ve retired. Recent research has found that thanks to the loss of FICA revenues resulting from COVID-19, the Social Security Trust Fund might run out of money four years earlier than predicted: as early as 2032. You may want to consider other forms of reliable income in case your benefits are reduced in the future.
Guaranteed Income
Speaking of reliable income, Olivia Mitchell, executive director of the Wharton School’s Pension Research Council, recommends that an annuity option become a staple in employer-sponsored retirement plans. Annuities generally offer an option for issuer-guaranteed income for life. With 10 years until retirement, allocating money to an annuity can help build a separate income stream to supplement Social Security benefits. Even if your employer doesn’t offer an annuity option in your 401(k) plan, you can purchase one separately using other assets.
Employer-Sponsored Retirement Plans
Speaking of the 401(k), consider that when this plan was first established in 1980, the marginal federal income tax rate was 43 percent. Today’s tax rates are historically quite low, so for the time being you might want to consider allocating more savings into a Roth IRA. This means you’ll pay taxes on that money at today’s low rates, but going forward it can grow tax-deferred and be withdrawn tax-free. But don’t leave money on the table if your employer offers a matching 401(k) contribution. Roth IRA contributions are limited to $7,000 (2020) and some deferred income can help reduce your taxes today – so plan accordingly.
Roth Conversion
By the same token, you may want to take advantage of today’s lower tax rates by converting at least some traditional IRA funds to a Roth or by making backdoor Roth IRA contributions. Be aware, however, that you must pay taxes on converted funds, so consider a gradual transition over multiple years to help you stay in a lower tax bracket.
Investor Portfolio
Some market analysts are predicting a “new normal” going forward, which could provide some interesting investment opportunities. Ideas include new operating business models based on a largely remote workforce, population spread as people move out of cities into more affordable rural areas, and innovations borne out of newly created demand. While a buy-and-hold strategy is a common advice for equities, it’s important to stay flexible. As long as you remain within your customized asset allocation strategy, you might want to use your equity portion to explore new ideas that could offer higher return opportunities over the next decade.
Tips for Retiring in the Next 10 Years
September 1, 2020 · Blog, Financial Planning
⏱ 4 min read
The stock market continues to perform with relative resilience, despite the current economic decline. But to be clear, without 100 percent participation in the economy – in terms of small business job creation, consumer spending, and company growth and expansion – the stock market is apt to reposition prices to reflect slower growth. With no containment or control of the pandemic on the horizon, there is plenty of uncertainty associated with future financial planning.
Anyone looking to retire in the next 10 years or so may want to take a fresh look at their current retirement income plan. In fact, they might need a Plan A, B, and C in order to stay flexible – with C being the option to continue working longer. The following are portfolio tips to consider for a 10-year time frame until retirement.
Emergency Fund
If there was one financial tip worth following pre-pandemic, it was to have liquid cash savings of six months to a year’s worth of expenses available. Workers who did are probably pretty relieved about now if they lost their job or had hours reduced. Having substantial cash available can save you from raiding retirement accounts and/or your investment portfolio.
In preparation for retirement, that cash buffer is even more important. Some advisors recommend a liquid savings fund to cover one to three years’ worth of expenses. That’s because once you’re on a fixed income, you’re not likely to replenish that account. What it can do is supplement variable retirement income that is reliant on the markets. Having a cash buffer gives investments time to recover from temporary losses so you don’t have to plunder your principal.
Status of Social Security
While you may know what your benefit level is for retirement at a certain date, be aware that your benefit could change – even after you’ve retired. Recent research has found that thanks to the loss of FICA revenues resulting from COVID-19, the Social Security Trust Fund might run out of money four years earlier than predicted: as early as 2032. You may want to consider other forms of reliable income in case your benefits are reduced in the future.
Guaranteed Income
Speaking of reliable income, Olivia Mitchell, executive director of the Wharton School’s Pension Research Council, recommends that an annuity option become a staple in employer-sponsored retirement plans. Annuities generally offer an option for issuer-guaranteed income for life. With 10 years until retirement, allocating money to an annuity can help build a separate income stream to supplement Social Security benefits. Even if your employer doesn’t offer an annuity option in your 401(k) plan, you can purchase one separately using other assets.
Employer-Sponsored Retirement Plans
Speaking of the 401(k), consider that when this plan was first established in 1980, the marginal federal income tax rate was 43 percent. Today’s tax rates are historically quite low, so for the time being you might want to consider allocating more savings into a Roth IRA. This means you’ll pay taxes on that money at today’s low rates, but going forward it can grow tax-deferred and be withdrawn tax-free. But don’t leave money on the table if your employer offers a matching 401(k) contribution. Roth IRA contributions are limited to $7,000 (2020) and some deferred income can help reduce your taxes today – so plan accordingly.
Roth Conversion
By the same token, you may want to take advantage of today’s lower tax rates by converting at least some traditional IRA funds to a Roth or by making backdoor Roth IRA contributions. Be aware, however, that you must pay taxes on converted funds, so consider a gradual transition over multiple years to help you stay in a lower tax bracket.
Investor Portfolio
Some market analysts are predicting a “new normal” going forward, which could provide some interesting investment opportunities. Ideas include new operating business models based on a largely remote workforce, population spread as people move out of cities into more affordable rural areas, and innovations borne out of newly created demand. While a buy-and-hold strategy is a common advice for equities, it’s important to stay flexible. As long as you remain within your customized asset allocation strategy, you might want to use your equity portion to explore new ideas that could offer higher return opportunities over the next decade.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
No surprise, but Americans are consuming and spending less since the coronavirus kicked in. Retail sales dropped to 8.7 percent in March, the largest month-over-month decline since the Census Bureau started tracking this data. Previously, the sharpest decline was less than half this – at 3.9 percent from October 2008 to November 2008, during the previous economic crisis. The reduction in consumer spending is due in part to lockdowns, spending more time at home for fear of the virus, and the economic impact – whether it’s losing a job, reduced hours, or in anticipation of tougher times ahead.
While consumer spending is down at a net level, there appear to be some winners and some losers in the post-COVID world of staying in and working from home. Restaurants and apparel are the hardest hit, whereas online retailers, home, garden, grocery, and alcohol sales are all up.
The decline and shift in consumer spending are having a strong negative impact on state sales tax revenues. Nationwide, sales taxes account for approximately 20 percent of all state revenue, so the decline in consumer spending will have a material impact on state budgets. As a result, states are looking at new ways to generate or increase revenue to offset the trend. Below we’ll look at three ways states are looking to raise taxes to make up for holes in their budgets.
Grocery Staples
Eating out less and working from home mean Americans are spending more at the grocery store; approximately 13 percent more year-over-year, per Census data. The issue for states is that groceries are generally not taxed or low-taxed, although there are a few items that apply the full tax rate.
Kansas, for example, applies the full sales tax rate to groceries. The consequence of this is that grocery sales make up about 15 percent of Kansas’ total sales tax revenue. The consequence of this policy is that the state’s sales tax revenue has barely taken a hit year-to-date.
States are taking notice and may move to the trend of taxing groceries as a way to recover part of their declining sales tax revenues.
Digital Taxes
Another trend is the increase in streaming services and one-time rentals/purchases of digital goods for entertainment and working at home. Currently, 22 states tax streaming services, and 30 states tax digital goods. Other states will look to start taxing these services as well, and digital taxes will start to expand into cloud storage and other services as more people work remotely.
Sin Taxes
Sin taxes are taxes on goods and services that are “bad” for us; think alcohol, tobacco, gambling, and marijuana (where it’s legal). Increases in sin taxes are generally easier to pass as they don’t apply to the overall general population and politicians can play the moral angle.
During the last recession, for example, lawmakers in more than 12 states increased tobacco and liquor taxes. Newer sin taxes are being instituted, such as those on vaping equipment and supplies.
Conclusion
The exact form and structure will vary, but one thing is certain: States will institute or increase taxes in areas where the money is being spent to ensure their sales tax revenue remains stable.
3 State Level Tax Hikes That Might Be Coming Due to COVID-19
September 1, 2020 · Blog, Tax and Financial News
⏱ 3 min read
No surprise, but Americans are consuming and spending less since the coronavirus kicked in. Retail sales dropped to 8.7 percent in March, the largest month-over-month decline since the Census Bureau started tracking this data. Previously, the sharpest decline was less than half this – at 3.9 percent from October 2008 to November 2008, during the previous economic crisis. The reduction in consumer spending is due in part to lockdowns, spending more time at home for fear of the virus, and the economic impact – whether it’s losing a job, reduced hours, or in anticipation of tougher times ahead.
While consumer spending is down at a net level, there appear to be some winners and some losers in the post-COVID world of staying in and working from home. Restaurants and apparel are the hardest hit, whereas online retailers, home, garden, grocery, and alcohol sales are all up.
The decline and shift in consumer spending are having a strong negative impact on state sales tax revenues. Nationwide, sales taxes account for approximately 20 percent of all state revenue, so the decline in consumer spending will have a material impact on state budgets. As a result, states are looking at new ways to generate or increase revenue to offset the trend. Below we’ll look at three ways states are looking to raise taxes to make up for holes in their budgets.
Grocery Staples
Eating out less and working from home mean Americans are spending more at the grocery store; approximately 13 percent more year-over-year, per Census data. The issue for states is that groceries are generally not taxed or low-taxed, although there are a few items that apply the full tax rate.
Kansas, for example, applies the full sales tax rate to groceries. The consequence of this is that grocery sales make up about 15 percent of Kansas’ total sales tax revenue. The consequence of this policy is that the state’s sales tax revenue has barely taken a hit year-to-date.
States are taking notice and may move to the trend of taxing groceries as a way to recover part of their declining sales tax revenues.
Digital Taxes
Another trend is the increase in streaming services and one-time rentals/purchases of digital goods for entertainment and working at home. Currently, 22 states tax streaming services, and 30 states tax digital goods. Other states will look to start taxing these services as well, and digital taxes will start to expand into cloud storage and other services as more people work remotely.
Sin Taxes
Sin taxes are taxes on goods and services that are “bad” for us; think alcohol, tobacco, gambling, and marijuana (where it’s legal). Increases in sin taxes are generally easier to pass as they don’t apply to the overall general population and politicians can play the moral angle.
During the last recession, for example, lawmakers in more than 12 states increased tobacco and liquor taxes. Newer sin taxes are being instituted, such as those on vaping equipment and supplies.
Conclusion
The exact form and structure will vary, but one thing is certain: States will institute or increase taxes in areas where the money is being spent to ensure their sales tax revenue remains stable.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Digital marketing is not a new phenomenon. However, new realities imposed by the COVID-19 pandemic have highlighted the importance of digital marketing for businesses. Basically, digital marketing revolves around using digital channels to advertise. Such channels include mobile devices, search engines, social media, websites, email, and others to help reach consumers. The purpose is to create a relationship with potential online customers to influence their buying decisions.
Why Digital Marketing
For starters, with digital marketing, you are able to personalize your marketing and target your ideal audience. It offers the ability to target an audience based on location, age, preference, and other specific details that define the intended consumer of your product or service. In the end, you don’t waste money on audiences that might not even buy your product or service.
With the availability of artificial intelligence, it’s easy to identify trends, carry out competitor research, and accumulate data that aid quick decision making. This kind of marketing is data-led. Considering that five to 10 hours of a person’s day is spent on the internet, this creates an opportunity to familiarize consumers with your brand and create relationships that lead to sales.
What’s more, chatbots are available on business websites or social media accounts to answer customer questions even when the business is closed. This means a customer visiting your page does not leave without some information that could help in their purchasing decision.
In addition to being able to expand your reach at a lower cost, your business can enhance brand loyalty by maintaining personal contact with clients even after making sales.
The best part of digital marketing is the ability to track the results of your marketing in real-time.
How This Can Help Grow Your Business
First, digital marketing gives all businesses a fair share of the market. Today, a business can connect with customers cheaply over posts on social media.
What this means is that a business can instantly communicate with customers to inform them of their products or services and get instant feedback.
Don’t ignore the fact that people today get information from the internet. A lot of purchase decisions start with an online search. A potential customer expects to find information regarding your products on a website, social media, or from reviews by other users.
Customers also want to determine if your business and products are a good fit for their needs.
In the event that they cannot locate your business, you will lose a potential client to a competitor.
A good online presence can help potential clients find you and possibly even become customers.
How to Get the Best of Digital Marketing
The good thing about digital marketing is that it will exist as long as people are using technology. The trick is to use strategies that help you stay ahead of the competition.
Digital marketing has been proven to be the best strategy to acquire new customers as well as maintain a relationship with existing customers.
One of the hard and fast rules about digital marketing is that no one strategy fits all businesses. Digital marketing is constantly changing – meaning that businesses have to make frequent changes to their strategies.
In order to stay ahead of the competition, you can take advantage of referral traffic as it gives credibility to your brand. This is possible by connecting with industry leaders in your niche.
You can’t afford to ignore analytics. Analytics help you discover what is working and what is not working.
Use high-quality content to draw the interest of potential customers. Sacrificing quality for volume can cost you potential leads.
Select social media platforms where your potential customers are likely to be. Understanding your target market will help you reduce the time and cost spent on digital marketing, as you will be able to follow your clients where they hang out.
Digital Marketing is the Way to Go
As long as the internet continues to grow, businesses have little choice but to get involved in digital marketing. Gone are the days when social media was considered merely a place to pass the time.
For some business owners, it might be challenging to know where and how to start, considering that digital marketing is quite an extensive field. The most important thing is to establish a goal for what you want to achieve. If not well done, it can cost your business a lot of unnecessary expense.
How to Make the Most of Digital Marketing
September 1, 2020 · Blog, What's New in Technology
⏱ 4 min read
Digital marketing is not a new phenomenon. However, new realities imposed by the COVID-19 pandemic have highlighted the importance of digital marketing for businesses. Basically, digital marketing revolves around using digital channels to advertise. Such channels include mobile devices, search engines, social media, websites, email, and others to help reach consumers. The purpose is to create a relationship with potential online customers to influence their buying decisions.
Why Digital Marketing
For starters, with digital marketing, you are able to personalize your marketing and target your ideal audience. It offers the ability to target an audience based on location, age, preference, and other specific details that define the intended consumer of your product or service. In the end, you don’t waste money on audiences that might not even buy your product or service.
With the availability of artificial intelligence, it’s easy to identify trends, carry out competitor research, and accumulate data that aid quick decision making. This kind of marketing is data-led. Considering that five to 10 hours of a person’s day is spent on the internet, this creates an opportunity to familiarize consumers with your brand and create relationships that lead to sales.
What’s more, chatbots are available on business websites or social media accounts to answer customer questions even when the business is closed. This means a customer visiting your page does not leave without some information that could help in their purchasing decision.
In addition to being able to expand your reach at a lower cost, your business can enhance brand loyalty by maintaining personal contact with clients even after making sales.
The best part of digital marketing is the ability to track the results of your marketing in real-time.
How This Can Help Grow Your Business
First, digital marketing gives all businesses a fair share of the market. Today, a business can connect with customers cheaply over posts on social media.
What this means is that a business can instantly communicate with customers to inform them of their products or services and get instant feedback.
Don’t ignore the fact that people today get information from the internet. A lot of purchase decisions start with an online search. A potential customer expects to find information regarding your products on a website, social media, or from reviews by other users.
Customers also want to determine if your business and products are a good fit for their needs.
In the event that they cannot locate your business, you will lose a potential client to a competitor.
A good online presence can help potential clients find you and possibly even become customers.
How to Get the Best of Digital Marketing
The good thing about digital marketing is that it will exist as long as people are using technology. The trick is to use strategies that help you stay ahead of the competition.
Digital marketing has been proven to be the best strategy to acquire new customers as well as maintain a relationship with existing customers.
One of the hard and fast rules about digital marketing is that no one strategy fits all businesses. Digital marketing is constantly changing – meaning that businesses have to make frequent changes to their strategies.
In order to stay ahead of the competition, you can take advantage of referral traffic as it gives credibility to your brand. This is possible by connecting with industry leaders in your niche.
You can’t afford to ignore analytics. Analytics help you discover what is working and what is not working.
Use high-quality content to draw the interest of potential customers. Sacrificing quality for volume can cost you potential leads.
Select social media platforms where your potential customers are likely to be. Understanding your target market will help you reduce the time and cost spent on digital marketing, as you will be able to follow your clients where they hang out.
Digital Marketing is the Way to Go
As long as the internet continues to grow, businesses have little choice but to get involved in digital marketing. Gone are the days when social media was considered merely a place to pass the time.
For some business owners, it might be challenging to know where and how to start, considering that digital marketing is quite an extensive field. The most important thing is to establish a goal for what you want to achieve. If not well done, it can cost your business a lot of unnecessary expense.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Small businesses nationwide were already facing cash problems before the COVID-19 pandemic, according to McKinsey & Company. The firm found that almost one-third of small businesses were either seeing losses or making just enough to stay in business, but not realizing profitability.
Looking at businesses selling essential and non-essential items, McKinsey & Company reports that before satisfying their “interest, taxes, depreciation and amortization” obligations and accountings, they were facing challenging times. When it comes to selling essential items, such as food, business owners in this industry only had margins of 5 percent. For businesses selling non-essential items, this sector saw margins of less than 10 percent.
Restaurants provide an example of one way that outfits can pivot and increase margins by modifying their business models. While the Harvard Business Review (HBR) explains that restaurants have created additional seating near the kitchen to maintain social distancing, other examples of business model changes include increasing takeout, delivery, and catering as a way to increase sales for businesses with limited in-store dining.
While these ideas are simply expanding upon existing models to make up for lost in-dining experiences, HBR offers another way that a restaurant can better distinguish its establishment: developing a subscription model for customers. By slimming down menu choices for more efficient and faster preparation, restaurants could give customers the option to receive a certain number of meals per week or day for a fixed price.
Increasing Margins
While there are different types of margins for business owners to keep an eye on, an important one is a gross margin and how it impacts a business’ bottom line. Since the onset of COVID-19, businesses have been trying to survive as we work our way through the pandemic.
Regardless of the type of product being sold, by reducing the number of options available to customers, businesses can increase their margins by still meeting customer demand for necessities while also getting better prices from their suppliers through larger orders. This strategy also can be applied with contract manufacturers.
Re-engineering products and the ingredients that go into them can help to increase margins. For example, if there is a variety of pre-packaged foods that sell for the same price, but there are specialty or costlier ingredients like meat instead of vegetables, pausing selling pre-packed meals with meat can increase profit margins.
McKinsey & Company explains that small businesses are able to increase their hygiene and safety protocols by encouraging and implementing contactless experiences. Along with reducing person-to-person contact by using mobile apps, restaurants also have made delivery and takeout a bigger part of their sales.
With small businesses like boutiques and farmers, HBR illustrates how these entities can explore different sales channels. With stores facing shortages and an inability to stock essential goods – especially food items – small farmers saw an opportunity to reinvent their business models after restaurants and gourmet markets dropped purchases from them during the stay-at-home orders.
An investment in an online presence, shipping and logistics, and sustained sales and marketing efforts have real potential for businesses to become profitable as trends point to a direct-to-consumer model. However, going with a digital storefront such as Shopify and selling directly to retail customers, HBR pointed out that some farmers are able to capture local customers (15 miles or less). This shows how farmers have been able to migrate from one source of revenue to another.
While the pandemic is ongoing, these are just a few ways that companies can implement new strategies to generate cash flow and attempt to survive the COVID-19 pandemic.
Three Strategies Companies Can Implement to Recover Faster
September 1, 2020 · Blog, General Business News
⏱ 4 min read
Small businesses nationwide were already facing cash problems before the COVID-19 pandemic, according to McKinsey & Company. The firm found that almost one-third of small businesses were either seeing losses or making just enough to stay in business, but not realizing profitability.
Looking at businesses selling essential and non-essential items, McKinsey & Company reports that before satisfying their “interest, taxes, depreciation and amortization” obligations and accountings, they were facing challenging times. When it comes to selling essential items, such as food, business owners in this industry only had margins of 5 percent. For businesses selling non-essential items, this sector saw margins of less than 10 percent.
Restaurants provide an example of one way that outfits can pivot and increase margins by modifying their business models. While the Harvard Business Review (HBR) explains that restaurants have created additional seating near the kitchen to maintain social distancing, other examples of business model changes include increasing takeout, delivery, and catering as a way to increase sales for businesses with limited in-store dining.
While these ideas are simply expanding upon existing models to make up for lost in-dining experiences, HBR offers another way that a restaurant can better distinguish its establishment: developing a subscription model for customers. By slimming down menu choices for more efficient and faster preparation, restaurants could give customers the option to receive a certain number of meals per week or day for a fixed price.
Increasing Margins
While there are different types of margins for business owners to keep an eye on, an important one is a gross margin and how it impacts a business’ bottom line. Since the onset of COVID-19, businesses have been trying to survive as we work our way through the pandemic.
Regardless of the type of product being sold, by reducing the number of options available to customers, businesses can increase their margins by still meeting customer demand for necessities while also getting better prices from their suppliers through larger orders. This strategy also can be applied with contract manufacturers.
Re-engineering products and the ingredients that go into them can help to increase margins. For example, if there is a variety of pre-packaged foods that sell for the same price, but there are specialty or costlier ingredients like meat instead of vegetables, pausing selling pre-packed meals with meat can increase profit margins.
McKinsey & Company explains that small businesses are able to increase their hygiene and safety protocols by encouraging and implementing contactless experiences. Along with reducing person-to-person contact by using mobile apps, restaurants also have made delivery and takeout a bigger part of their sales.
With small businesses like boutiques and farmers, HBR illustrates how these entities can explore different sales channels. With stores facing shortages and an inability to stock essential goods – especially food items – small farmers saw an opportunity to reinvent their business models after restaurants and gourmet markets dropped purchases from them during the stay-at-home orders.
An investment in an online presence, shipping and logistics, and sustained sales and marketing efforts have real potential for businesses to become profitable as trends point to a direct-to-consumer model. However, going with a digital storefront such as Shopify and selling directly to retail customers, HBR pointed out that some farmers are able to capture local customers (15 miles or less). This shows how farmers have been able to migrate from one source of revenue to another.
While the pandemic is ongoing, these are just a few ways that companies can implement new strategies to generate cash flow and attempt to survive the COVID-19 pandemic.
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Law Enforcement Suicide Data Collection Act (S 2746) – This bill authorizes the establishment of a new Law Enforcement Officers Suicide Data Collection Program to be administered by the FBI. The program will gather data related to suicides and attempted suicides of current and former officers, as well as the wrongful detainment of U.S. nationals abroad. The purpose of the Act is to help understand and prevent law enforcement suicides. The bill was introduced by Sen. Catherine Cortez Masto (D-NV) on Oct. 30, 2019. It was passed by the House and the Senate in May and was signed into law on June 16.
Uyghur Human Rights Policy Act of 2020 (S 2744) – Sen. Marco Rubio (R-FL) introduced this legislation on May 14 as a means to condemn human rights violations of ethnic Turkic Muslims in Xinjiang. The bill calls for an end to the arbitrary detention, torture and harassment of these communities inside and outside of China. The Act was passed by both the Senate and the House in May and was signed into law by the president on June 17.
Hong Kong Autonomy Act (HR 7440) – Introduced by Rep. Brad Sherman (D-CA) on July 1, this legislation authorizes the president to sanction foreign individuals, entities and financial institutions that materially contribute to China’s failure to preserve Hong Kong’s autonomy in response to a written report to be submitted by the State Department each year. While the bill also gives the president the authority to waive or terminate sanctions, it permits Congress to override such an action by passing a joint resolution of disapproval. The Act was unanimously passed in Congress and signed into law by the president on July 14.
Emergency Aid for Returning Americans Affected by Coronavirus Act (S 4091) – This bill was introduced by Sen. Chuck Grassley (R-IA) to amend section 1113 of the Social Security Act. The Act authorizes funding for fiscal year 2020 in order to increase payments for temporary assistance to U.S. citizens and their dependents who return from foreign countries due to the COVID-19 crisis and are without available resources. The legislation enables the Department of Health and Human Services to provide monetary payments and medical care on a temporary basis. The Act was introduced and passed in both the House and Senate on June 29 and signed into law on July 13.
Protecting Nonprofits from Catastrophic Cash Flow Strain Act of 2020 (S 4209) – This bill is designed to improve emergency unemployment relief for governmental entities and nonprofit organizations by amending Title IX of the Social Security Act. The bill was introduced by Sen. Tim Scott (R-SC) on July 2. It was passed in the House and in the Senate on July 9, and is currently awaiting signature by the president.
Moving Forward Act (HR 2) – On June 11, this Act was introduced by Rep. Peter Defazio (D-OR). This bill would authorize funding for federal highways, highway safety programs and transit programs. It also addresses climate change strategies to reduce weather impacts on surface transportation by conducting a vulnerability assessment and recommending ways to enhance resilience for highways, mass transit and rail. The bill would allocate a grant program to help improve the safety, state of good repair and connectivity of transportation infrastructure in rural communities. It also directs the Department of Transportation to establish a pilot program for a national motor vehicle per-mile user fee to restore and maintain the long-term solvency of the Highway Trust Fund to uphold a state of good repair for the future. The bill passed in the House on July 1 and is currently in the Senate, where it enjoys considerable bipartisan support for infrastructure projects.
Relief and Funding for Human Rights, Emergency Aid, Cash-Flow Assistance and New Infrastructure Projects
August 1, 2020 · Blog, Congress at Work
⏱ 3 min read
Law Enforcement Suicide Data Collection Act (S 2746) – This bill authorizes the establishment of a new Law Enforcement Officers Suicide Data Collection Program to be administered by the FBI. The program will gather data related to suicides and attempted suicides of current and former officers, as well as the wrongful detainment of U.S. nationals abroad. The purpose of the Act is to help understand and prevent law enforcement suicides. The bill was introduced by Sen. Catherine Cortez Masto (D-NV) on Oct. 30, 2019. It was passed by the House and the Senate in May and was signed into law on June 16.
Uyghur Human Rights Policy Act of 2020 (S 2744) – Sen. Marco Rubio (R-FL) introduced this legislation on May 14 as a means to condemn human rights violations of ethnic Turkic Muslims in Xinjiang. The bill calls for an end to the arbitrary detention, torture and harassment of these communities inside and outside of China. The Act was passed by both the Senate and the House in May and was signed into law by the president on June 17.
Hong Kong Autonomy Act (HR 7440) – Introduced by Rep. Brad Sherman (D-CA) on July 1, this legislation authorizes the president to sanction foreign individuals, entities and financial institutions that materially contribute to China’s failure to preserve Hong Kong’s autonomy in response to a written report to be submitted by the State Department each year. While the bill also gives the president the authority to waive or terminate sanctions, it permits Congress to override such an action by passing a joint resolution of disapproval. The Act was unanimously passed in Congress and signed into law by the president on July 14.
Emergency Aid for Returning Americans Affected by Coronavirus Act (S 4091) – This bill was introduced by Sen. Chuck Grassley (R-IA) to amend section 1113 of the Social Security Act. The Act authorizes funding for fiscal year 2020 in order to increase payments for temporary assistance to U.S. citizens and their dependents who return from foreign countries due to the COVID-19 crisis and are without available resources. The legislation enables the Department of Health and Human Services to provide monetary payments and medical care on a temporary basis. The Act was introduced and passed in both the House and Senate on June 29 and signed into law on July 13.
Protecting Nonprofits from Catastrophic Cash Flow Strain Act of 2020 (S 4209) – This bill is designed to improve emergency unemployment relief for governmental entities and nonprofit organizations by amending Title IX of the Social Security Act. The bill was introduced by Sen. Tim Scott (R-SC) on July 2. It was passed in the House and in the Senate on July 9, and is currently awaiting signature by the president.
Moving Forward Act (HR 2) – On June 11, this Act was introduced by Rep. Peter Defazio (D-OR). This bill would authorize funding for federal highways, highway safety programs and transit programs. It also addresses climate change strategies to reduce weather impacts on surface transportation by conducting a vulnerability assessment and recommending ways to enhance resilience for highways, mass transit and rail. The bill would allocate a grant program to help improve the safety, state of good repair and connectivity of transportation infrastructure in rural communities. It also directs the Department of Transportation to establish a pilot program for a national motor vehicle per-mile user fee to restore and maintain the long-term solvency of the Highway Trust Fund to uphold a state of good repair for the future. The bill passed in the House on July 1 and is currently in the Senate, where it enjoys considerable bipartisan support for infrastructure projects.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.




 Due to the uncertainty of COVID-19, many schools across America have transitioned to at-home learning. This alone presents a whole new set of challenges for parents, not the least of which is figuring out what to feed your kids for lunch – every single day of the week. While peanut butter and jelly is a reliable standby, here are some cheap, easy alternatives you can whip up in no time.
 As bad as the economy is right now due to the COVID outbreak in the United States, many economists are predicting that the long-term outlook is much bleaker. Alas, Congress and the Federal Reserve’s efforts at stimulus and interest rate management have done much to keep the economy and stock market afloat. However, small businesses – the backbone of America’s employment growth – are closing every day. As consumer spending reduces further, the impact will likely affect Wall Street. Consequently, share prices may soon begin correcting to reflect the future more so than the present.
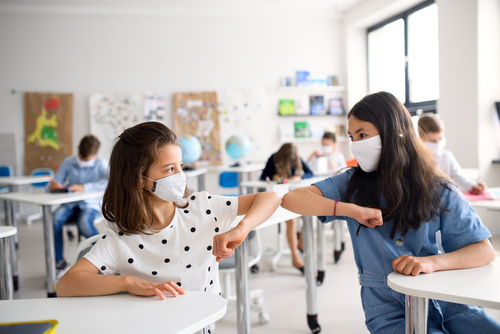 If you’re anxious about sending your children back to school, you’re not alone. In fact, a recent poll from
 A bill to amend the Servicemembers Civil Relief Act to extend lease protections for servicemembers under stop movement orders in response to a local, national, or global emergency, and for other purposes (S 3637) – This bill extends the Servicemembers Civil Relief Act to protect service members who were previously issued orders to change duty stations but had those orders rescinded because of the pandemic. A stop movement order may leave them with a housing and/or car lease in two different locations. This extension allows families who are unable to relocate due to pandemic-related travel restrictions to be released without penalty from their leases. It is retroactive to March 1, 2020. The bill was introduced by Sen. Jon Tester (D-MT) on May 6. It was passed by the Senate in June, the House in July, and was signed by the President on Aug. 14.
 The stock market continues to perform with relative resilience, despite the current economic decline. But to be clear, without 100 percent participation in the economy – in terms of small business job creation, consumer spending, and company growth and expansion – the stock market is apt to reposition prices to reflect slower growth. With no containment or control of the pandemic on the horizon, there is plenty of uncertainty associated with future financial planning.
 No surprise, but Americans are consuming and spending less since the coronavirus kicked in. Retail sales dropped to 8.7 percent in March, the largest month-over-month decline since the Census Bureau started tracking this data. Previously, the sharpest decline was less than half this – at 3.9 percent from October 2008 to November 2008, during the previous economic crisis. The reduction in consumer spending is due in part to lockdowns, spending more time at home for fear of the virus, and the economic impact – whether it’s losing a job, reduced hours, or in anticipation of tougher times ahead.
 Digital marketing is not a new phenomenon. However, new realities imposed by the COVID-19 pandemic have highlighted the importance of digital marketing for businesses. Basically, digital marketing revolves around using digital channels to advertise. Such channels include mobile devices, search engines, social media, websites, email, and others to help reach consumers. The purpose is to create a relationship with potential online customers to influence their buying decisions.
 Small businesses nationwide were already facing cash problems before the COVID-19 pandemic, according to McKinsey & Company. The firm found that almost one-third of small businesses were either seeing losses or making just enough to stay in business, but not realizing profitability.
 Law Enforcement Suicide Data Collection Act (S 2746) – This bill authorizes the establishment of a new Law Enforcement Officers Suicide Data Collection Program to be administered by the FBI. The program will gather data related to suicides and attempted suicides of current and former officers, as well as the wrongful detainment of U.S. nationals abroad. The purpose of the Act is to help understand and prevent law enforcement suicides. The bill was introduced by Sen. Catherine Cortez Masto (D-NV) on Oct. 30, 2019. It was passed by the House and the Senate in May and was signed into law on June 16.