The first Payroll Protection Program (PPP) loans were made over eight weeks ago, which means they may be forgivable if the guidelines set forth by the Small Business Administration (SBA) and the United States Treasury Department are met.
In order to have a loan forgiven, borrowers need to complete the 11-page application made available by the Treasury Department. Applicants can complete the forms either in hard copy or via an online platform if provided by their lender. Large borrowers, or those who took out more than $2 million from the PPP program, are required to file even more paperwork.
Along with the application, borrowers need to submit a Forgiveness Amount Calculation. This calculation discloses the total eligible payroll costs paid during the program. Applicants will also need documentation, such as tax filing statements, utilities, PPP loan contracts, EIDL contracts, and any supporting documents that were used when applying for the PPP loan.
Certification of the loan forgiveness amount requested is necessary to prove it was truly used to pay eligible costs, such as payroll, business mortgage interest, rent or lease payments, and utilities. Further, borrowers must report any declines in the number of full-time equivalent employees (FTEs) and/or wage reductions more than 25 percent. Failing to retain pre-program FTE headcount or wage reductions over this threshold will reduce the eligible amount of loan forgiveness.
The amount of paperwork necessary to substantiate the application can be daunting, especially for many “main street” businesses. In order to help you complete the application, the SBA has issued formal guidance that can be found here. And a more user-friendly guide giving detailed instructions on how to fill out your PPP forgiveness application form can be found here, provided by Bench.We can assist you with the application process itself and the required documentation. Give us a call to see how we can help instead of struggling through the process on your own.
Payroll Protection Program Loan Forgiveness is Here
June 1, 2020 · Blog, Guest Post of the Month
⏱ 2 min read
The first Payroll Protection Program (PPP) loans were made over eight weeks ago, which means they may be forgivable if the guidelines set forth by the Small Business Administration (SBA) and the United States Treasury Department are met.
In order to have a loan forgiven, borrowers need to complete the 11-page application made available by the Treasury Department. Applicants can complete the forms either in hard copy or via an online platform if provided by their lender. Large borrowers, or those who took out more than $2 million from the PPP program, are required to file even more paperwork.
Along with the application, borrowers need to submit a Forgiveness Amount Calculation. This calculation discloses the total eligible payroll costs paid during the program. Applicants will also need documentation, such as tax filing statements, utilities, PPP loan contracts, EIDL contracts, and any supporting documents that were used when applying for the PPP loan.
Certification of the loan forgiveness amount requested is necessary to prove it was truly used to pay eligible costs, such as payroll, business mortgage interest, rent or lease payments, and utilities. Further, borrowers must report any declines in the number of full-time equivalent employees (FTEs) and/or wage reductions more than 25 percent. Failing to retain pre-program FTE headcount or wage reductions over this threshold will reduce the eligible amount of loan forgiveness.
The amount of paperwork necessary to substantiate the application can be daunting, especially for many “main street” businesses. In order to help you complete the application, the SBA has issued formal guidance that can be found here. And a more user-friendly guide giving detailed instructions on how to fill out your PPP forgiveness application form can be found here, provided by Bench.We can assist you with the application process itself and the required documentation. Give us a call to see how we can help instead of struggling through the process on your own.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With the coronavirus spreading across the globe, catching individuals and governments off guard, business owners have not fared any better. While the virus is having a grave impact on the health of millions across the globe, businesses have seen an equally serious impact on their bottom line. The virus is projected to hit businesses’ cash-flow and the ability to stay open post-pandemic.
While different parts of the country have been hit harder than others, the nation’s businesses, their owners, and employees are all dependent on the national and global economy. Looking to those who have survived past crises, business owners are now tasked with guiding their organizations through the coronavirus pandemic.
Effective Attributes and Responses to Help with Recovery
Right now, more than ever, it is equally important that business owners empathize with their clients’ expectations and their employees’ needs while also taking steps to maintain their financial health.
Other attributes of effective business owners include making sound judgments in light of limited or incomplete data, along with providing a positive but realistic forecast of the situation to keep the employees motivated and productive. Lastly, leaders who see crises like the coronavirus as opportunities to identify trends for innovation and ways to problem solve can look to brighter days in the future.
Protecting the Business’ Bottom-Line
Like other sustained business interruption events, there’s a three-pronged approach that businesses can implement to increase their chances of survival. The first is to manage the shock from the initial impact and establish a protocol for the new normal in order to preserve continuity. The next step is to learn from what has occurred and adapt to the way work is now being performed to serve clients as effectively as before. The final step is to identify future opportunities to operate differently, more efficiently, and gear up for the post-crisis new normal.
To better mitigate major effects from a crisis and begin the adaptation process, the following are practical steps to emerge leaner and more efficient as the reopening process begins. Two primary actions that businesses must take is to first protect the well-being of workers, while also protecting the business financially.
Making decisions should be streamlined because a lack of certainty can give decision-makers analysis paralysis. This can slow down important steps needing to be made faster than during non-crisis times. Moving from a chain of command to collaborative teams to make decisions can increase speed by having fewer steps and faster decision-making processes.
Documenting all cash the business holds, along with committed and uncommitted lines of credit, also is suggested. Be sure to include lines that are pre-established with banks or credit unions, plus any existing borrowing limits from lenders; this will provide a baseline for businesses to make crisis projections. Other liquidity measures might be negotiating to extend better payment terms and refinancing existing lines of credit for better short-term payments, potential new equity injections, etc.
Quickly modeling different economic outlooks for existing markets that are served, depending on how mild, moderate, or severe the crisis impacts that business, can provide greater insight on a business’ financials. As conditions change, it will become evident how much cash is needed and what areas of a business might need to be scaled back or cut. Leaders should also look at the likelihood of not being able to serve outstanding debt, primarily as they look at liquidity and the profitability of the business’ operations.
Determine the business’ mission-critical business segments. This looks at which services or products are most profitable and/or resource-intensive. This will help determine which ones are important to current and future cash flow and which segments could be impacted based on the length and severity of the crisis.
Evaluate what businesses can do to reduce non-essential or discretionary expenses to positively impact its finances. This can be accomplished by reducing or forgoing landscaping a business’ exterior or holding off on repainting a building. It can also come in the form of reducing one shift or reducing spending on employee training.
Since the coronavirus is a fluid crisis and there are many possible outcomes, business owners will implement different practices based on how this crisis evolves. Depending on the severity of the actual impact, different products or services can be stopped temporarily, employees’ hours can be reduced or a hiring freeze can be implemented.
COVID-19 Recovery Responses are Crucial for Companies to Thrive in the Future
May 5, 2020 · Blog, Guest Post of the Month
⏱ 4 min read
With the coronavirus spreading across the globe, catching individuals and governments off guard, business owners have not fared any better. While the virus is having a grave impact on the health of millions across the globe, businesses have seen an equally serious impact on their bottom line. The virus is projected to hit businesses’ cash-flow and the ability to stay open post-pandemic.
While different parts of the country have been hit harder than others, the nation’s businesses, their owners, and employees are all dependent on the national and global economy. Looking to those who have survived past crises, business owners are now tasked with guiding their organizations through the coronavirus pandemic.
Effective Attributes and Responses to Help with Recovery
Right now, more than ever, it is equally important that business owners empathize with their clients’ expectations and their employees’ needs while also taking steps to maintain their financial health.
Other attributes of effective business owners include making sound judgments in light of limited or incomplete data, along with providing a positive but realistic forecast of the situation to keep the employees motivated and productive. Lastly, leaders who see crises like the coronavirus as opportunities to identify trends for innovation and ways to problem solve can look to brighter days in the future.
Protecting the Business’ Bottom-Line
Like other sustained business interruption events, there’s a three-pronged approach that businesses can implement to increase their chances of survival. The first is to manage the shock from the initial impact and establish a protocol for the new normal in order to preserve continuity. The next step is to learn from what has occurred and adapt to the way work is now being performed to serve clients as effectively as before. The final step is to identify future opportunities to operate differently, more efficiently, and gear up for the post-crisis new normal.
To better mitigate major effects from a crisis and begin the adaptation process, the following are practical steps to emerge leaner and more efficient as the reopening process begins. Two primary actions that businesses must take is to first protect the well-being of workers, while also protecting the business financially.
Making decisions should be streamlined because a lack of certainty can give decision-makers analysis paralysis. This can slow down important steps needing to be made faster than during non-crisis times. Moving from a chain of command to collaborative teams to make decisions can increase speed by having fewer steps and faster decision-making processes.
Documenting all cash the business holds, along with committed and uncommitted lines of credit, also is suggested. Be sure to include lines that are pre-established with banks or credit unions, plus any existing borrowing limits from lenders; this will provide a baseline for businesses to make crisis projections. Other liquidity measures might be negotiating to extend better payment terms and refinancing existing lines of credit for better short-term payments, potential new equity injections, etc.
Quickly modeling different economic outlooks for existing markets that are served, depending on how mild, moderate, or severe the crisis impacts that business, can provide greater insight on a business’ financials. As conditions change, it will become evident how much cash is needed and what areas of a business might need to be scaled back or cut. Leaders should also look at the likelihood of not being able to serve outstanding debt, primarily as they look at liquidity and the profitability of the business’ operations.
Determine the business’ mission-critical business segments. This looks at which services or products are most profitable and/or resource-intensive. This will help determine which ones are important to current and future cash flow and which segments could be impacted based on the length and severity of the crisis.
Evaluate what businesses can do to reduce non-essential or discretionary expenses to positively impact its finances. This can be accomplished by reducing or forgoing landscaping a business’ exterior or holding off on repainting a building. It can also come in the form of reducing one shift or reducing spending on employee training.
Since the coronavirus is a fluid crisis and there are many possible outcomes, business owners will implement different practices based on how this crisis evolves. Depending on the severity of the actual impact, different products or services can be stopped temporarily, employees’ hours can be reduced or a hiring freeze can be implemented.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Since the escalation of COVID-19 cases, malicious activity from cybercriminals is also on the rise.
Hackers are taking advantage of the coronavirus fear to carry out attacks. This is done by creating websites that claim to have cures for the virus or by spreading emails that contain links to malware.
Consider this research by Check Point, where they found an increase in coronavirus domain name registration. Most of these scam websites allege to be selling vaccines against the virus.
At the beginning of this year, one of the reported cases was the Emotet malware that was used in a coronavirus-themed campaign in Japan. Phishing victims received an email purporting to report locations where the infection was spreading. Because the email appeared to be an official communication from the government, victims were likely to open it to find out more about the information. However, an attempt to open a .docx document will download the Emotet malware to the victim’s computer.
Apart from a .docx, the attachment could be a .pdf or an .mp4 claiming to have instructions on how to protect against the virus or other related updates.
The case in Japan is among the first attacks on the public domain that came with the rise of the COVID-19. Since then as the coronavirus continued to spread, more data breach cases have been reported. According to Malwarebytes Labs director Jerome Segura, there is an increase in campaigns that use the coronavirus situation to trick victims. Segura reports that in March alone, there was a 26 percent increase in online credit card skimming as people did online shopping from the safety of their homes.
Even the World Health Organization has not been spared, as they recently reported a fivefold increase in cyberattacks. The attacks have increased such that there was a joint alert sent out by the United States Department of Homeland Security, the Cybersecurity and Infrastructure Security Agency, and the United Kingdom’s National Cyber Security Centre.
Unfortunately, the fact is it won’t get any better as more cybersecurity firms report an increase in attacks relating to the coronavirus outbreak. This is because attacks that are based on important events or occurrences such as the COVID-19 pandemic become effective as they leverage on the public’s need to know.
In matters of life and death, people tend to be less careful; and in an attempt to stay informed, they end up becoming victims of cybercriminals.
Apart from malware, there are fears that work-at-home directives also have led to an increase in data breaches. If you have a business, you probably have policies to help guard against cyberattacks. However, since the work-at-home situation was largely unplanned and employees are having to work from home, data can be easily leaked from the devices they use to connect to the office network.
It’s important to keep in mind that hackers love to take advantage of current events to trick their victims. Because of this, it’s expected that these attacks will increase in frequency – and this calls for users to be vigilant.
Although security systems might already be in place, none of them have the ability to deal with ever-increasing threats that have grown in sophistication. Email security remains one of the hardest challenges for employers. However, taking precautionary measures will help reduce the possibility of successful attacks.
Here are 10 ways to keep safe:
Avoid clicking on promotional links in emails.
Be careful when you receive emails with subject lines that include coronavirus or COVID-19 and have a call to action.
Be careful when clicking on pages with special offers, especially pages claiming to sell or know about the cure for the coronavirus.
Check domain names to verify their validity.
Be careful about clicking on links found on SMS that claim to come from institutions such as your credit company or bank; such links could activate the malware.
Make sure to use a virtual private network (VPN) – especially when working with sensitive data.
If you have a business and your employees are using corporate devices, enable remote wipe in case devices to get compromised or lost.
Limit the number of times you enter your credit card details online and confirm that the domain where you enter personal information is legitimate.
Hackers will continue to adjust their tactics; therefore, use trusted resources such as the Centers for Disease Control and Prevention for information on the coronavirus.
Use strong passwords.
Heightened Hacking as Corona Pandemic Worsens; How to Avoid Being a Victim
May 1, 2020 · Blog, What's New in Technology
⏱ 4 min read
Since the escalation of COVID-19 cases, malicious activity from cybercriminals is also on the rise.
Hackers are taking advantage of the coronavirus fear to carry out attacks. This is done by creating websites that claim to have cures for the virus or by spreading emails that contain links to malware.
Consider this research by Check Point, where they found an increase in coronavirus domain name registration. Most of these scam websites allege to be selling vaccines against the virus.
At the beginning of this year, one of the reported cases was the Emotet malware that was used in a coronavirus-themed campaign in Japan. Phishing victims received an email purporting to report locations where the infection was spreading. Because the email appeared to be an official communication from the government, victims were likely to open it to find out more about the information. However, an attempt to open a .docx document will download the Emotet malware to the victim’s computer.
Apart from a .docx, the attachment could be a .pdf or an .mp4 claiming to have instructions on how to protect against the virus or other related updates.
The case in Japan is among the first attacks on the public domain that came with the rise of the COVID-19. Since then as the coronavirus continued to spread, more data breach cases have been reported. According to Malwarebytes Labs director Jerome Segura, there is an increase in campaigns that use the coronavirus situation to trick victims. Segura reports that in March alone, there was a 26 percent increase in online credit card skimming as people did online shopping from the safety of their homes.
Even the World Health Organization has not been spared, as they recently reported a fivefold increase in cyberattacks. The attacks have increased such that there was a joint alert sent out by the United States Department of Homeland Security, the Cybersecurity and Infrastructure Security Agency, and the United Kingdom’s National Cyber Security Centre.
Unfortunately, the fact is it won’t get any better as more cybersecurity firms report an increase in attacks relating to the coronavirus outbreak. This is because attacks that are based on important events or occurrences such as the COVID-19 pandemic become effective as they leverage on the public’s need to know.
In matters of life and death, people tend to be less careful; and in an attempt to stay informed, they end up becoming victims of cybercriminals.
Apart from malware, there are fears that work-at-home directives also have led to an increase in data breaches. If you have a business, you probably have policies to help guard against cyberattacks. However, since the work-at-home situation was largely unplanned and employees are having to work from home, data can be easily leaked from the devices they use to connect to the office network.
It’s important to keep in mind that hackers love to take advantage of current events to trick their victims. Because of this, it’s expected that these attacks will increase in frequency – and this calls for users to be vigilant.
Although security systems might already be in place, none of them have the ability to deal with ever-increasing threats that have grown in sophistication. Email security remains one of the hardest challenges for employers. However, taking precautionary measures will help reduce the possibility of successful attacks.
Here are 10 ways to keep safe:
Avoid clicking on promotional links in emails.
Be careful when you receive emails with subject lines that include coronavirus or COVID-19 and have a call to action.
Be careful when clicking on pages with special offers, especially pages claiming to sell or know about the cure for the coronavirus.
Check domain names to verify their validity.
Be careful about clicking on links found on SMS that claim to come from institutions such as your credit company or bank; such links could activate the malware.
Make sure to use a virtual private network (VPN) – especially when working with sensitive data.
If you have a business and your employees are using corporate devices, enable remote wipe in case devices to get compromised or lost.
Limit the number of times you enter your credit card details online and confirm that the domain where you enter personal information is legitimate.
Hackers will continue to adjust their tactics; therefore, use trusted resources such as the Centers for Disease Control and Prevention for information on the coronavirus.
Use strong passwords.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
During the government shutdown as a result of COVID-19, sadly, millions have lost their jobs. However, there is a silver lining: there are some industries that, because of the shutdown, are actually hiring. Here are a few leads to help those who might have been affected.
Shipping and Delivery
This industry is hiring at what seems like warp speed. It’s reported that Amazon has created 100,000 jobs, specifically for fulfillment and delivery. UPS is hiring, as are courier services. Search “courier services hiring near me” to find opportunities. You might be surprised by what you find.
National Retailers
In addition to Amazon, there are other giants that are hiring, including CVS, Kroger, and Walmart. See the entire list here. The National Retail Federation also has a good list, which includes GE Healthcare, The Home Depot, and Instacart (the latter is a big one, as many don’t want to darken the doors of grocery stores). Access everything here.
Online Learning Companies
Now that scores of kids are at home, teachers are in demand to assist with online learning. Outschool is hiring thousands of teachers. GetEducated is also a great resource for finding a list of companies that are looking for online teachers. And if you’ve always wanted to be a teacher, now’s a good time as any because you can earn online credentials. The world always needs great educators!
Remote Meeting and Communication Companies
Since many companies must conduct business remotely, outfits such as Zoom, Slack, and Microsoft Teams are hiring. Furthermore, since aspects of COVID-19 are still unfolding and may require a longer stint of working at home, these companies could be hiring for a good while, meaning this burst of openings might not be just a flash in the pan.
Childcare
Now that many parents are working from home, they still need childcare. Though our situation changes daily, the California governor announced that schools likely won’t open before fall. Think about opening up your home with affordable, flexible options. It could become a whole new business for you.
Healthcare
While this might not be the first choice for some, it is a sector that’s hiring, not surprisingly. According to an article on LinkedIn, healthcare job postings spiked 35 percent compared to just a few months before the shutdown. Demand is intense in New York and New Jersey. However, California, Florida, Texas, and Arizona are growth markets as well. Check out your local hospitals or freestanding care clinics.
Think Outside the Box
Right now during a pandemic, there’s no shame in taking a job for which you might not be a perfect fit, or even overqualified. Money is money. However, if you feel you need to learn skills for a particular job or if you want to learn something new just because, now is the time to do so. Want to learn to code? Try your hand at the GRE? Pick up an online credential? There’s no time like the present. Go for it!
During the government shutdown as a result of COVID-19, sadly, millions have lost their jobs. However, there is a silver lining: there are some industries that, because of the shutdown, are actually hiring. Here are a few leads to help those who might have been affected.
Shipping and Delivery
This industry is hiring at what seems like warp speed. It’s reported that Amazon has created 100,000 jobs, specifically for fulfillment and delivery. UPS is hiring, as are courier services. Search “courier services hiring near me” to find opportunities. You might be surprised by what you find.
National Retailers
In addition to Amazon, there are other giants that are hiring, including CVS, Kroger, and Walmart. See the entire list here. The National Retail Federation also has a good list, which includes GE Healthcare, The Home Depot, and Instacart (the latter is a big one, as many don’t want to darken the doors of grocery stores). Access everything here.
Online Learning Companies
Now that scores of kids are at home, teachers are in demand to assist with online learning. Outschool is hiring thousands of teachers. GetEducated is also a great resource for finding a list of companies that are looking for online teachers. And if you’ve always wanted to be a teacher, now’s a good time as any because you can earn online credentials. The world always needs great educators!
Remote Meeting and Communication Companies
Since many companies must conduct business remotely, outfits such as Zoom, Slack, and Microsoft Teams are hiring. Furthermore, since aspects of COVID-19 are still unfolding and may require a longer stint of working at home, these companies could be hiring for a good while, meaning this burst of openings might not be just a flash in the pan.
Childcare
Now that many parents are working from home, they still need childcare. Though our situation changes daily, the California governor announced that schools likely won’t open before fall. Think about opening up your home with affordable, flexible options. It could become a whole new business for you.
Healthcare
While this might not be the first choice for some, it is a sector that’s hiring, not surprisingly. According to an article on LinkedIn, healthcare job postings spiked 35 percent compared to just a few months before the shutdown. Demand is intense in New York and New Jersey. However, California, Florida, Texas, and Arizona are growth markets as well. Check out your local hospitals or freestanding care clinics.
Think Outside the Box
Right now during a pandemic, there’s no shame in taking a job for which you might not be a perfect fit, or even overqualified. Money is money. However, if you feel you need to learn skills for a particular job or if you want to learn something new just because, now is the time to do so. Want to learn to code? Try your hand at the GRE? Pick up an online credential? There’s no time like the present. Go for it!
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The third decade of the 21st century started out with a vigorous economy, record low unemployment levels, and benign inflation. But late in the first quarter over the span of two weeks, investors faced the fastest stock market correction in history.
With an unpredictable assailant like a global virus, short-term actions by Congress and the Federal Reserve will need time to see if they are effective. Ultimately, the fate of the U.S. and global economies, which in turn will impact the investment markets, is dependent on how long the COVID-19 outbreak continues and if there is a second wave. Clearly, both supply and demand have been dramatically reduced, with a ripple effect on companies, workers, consumers, and investors. Once the crisis has passed, we will learn which sectors, industries, and individual companies remain financially viable with a business model built to sustain this unprecedented economic fallout.
Amid this backdrop, wealth managers must read the tea leaves to anticipate what the investment markets will look like post-coronavirus. The challenge is how to best position assets to take advantage of future gains without giving up ground now and turning paper losses into permanent shortfalls.
For individual investors, it comes down to what you want to accomplish in the next decade – or what your money can accomplish for you. Are you nearing retirement? Will you remain in the accumulation phase, wherein you can afford to take on market risk? Are you just starting out, and are you risk-averse due to the two major economic declines experienced in your relatively short life, or are you prepared to invest in future prospects – wherever they may lie?
Anyone already in or nearing retirement would do well to invest for a steady stream of income. While the DJIA initially took a beating, many blue-chip stalwarts continue to grow and payout dividends as they have long term, through thick and thin. However, pay attention here, as there are some long-standing dividend-paying companies that are starting to suspend or substantially cut dividend payments.
Growth-oriented investors would do well to look at companies that were well-positioned to survive the pandemic, because they may well represent commerce of the future. This includes the well-established FAANG stocks (Facebook, Apple, Amazon, Netflix, and Google), which have become masters of fast and reliable delivery of online content and physical delivery of essential and discretionary products. Unfortunately, the stock prices of these companies have soared in recent years, so it’s time to consider what the “next big thing” in this arena will look like and who are the frontrunners.
With that in mind, take a look at 2020 demographics. Millennials recently surpassed Baby Boomers as the largest generation in the United States, but they aren’t expected to hold this mantle for long. Generation Z/Centennials are on track to enter the workforce in higher numbers during the next decade. This is a generation that has never known life without cell phones and the internet, so expect the technology sector to ramp up not just with consumer innovations, but with ways to help other industries enhance data management, blockchain supply chains, and artificial intelligence – which might become as omnipresent as retail strip malls.
In a post-pandemic world, employers seeking to strengthen their business models might come to embrace the idea of foregoing healthcare and other expensive benefits offered to employees. A subsequent world of higher pay and more public options could spur the growth of entrepreneurship and new small businesses. By taking advantage of remote employees, low overhead expenses, and emerging technologies, smaller companies or conglomerates might be able to compete with the likes of Amazon in both domestic and global markets.
As a short-term precaution, consider how you might defend your portfolio against the possibility of inflation as we stumble out of the pandemic economy. The federal government’s generous stimulus packages combined with a continued easing of monetary policy by the Federal Reserve could lead the United States to higher inflation. This could be exacerbated by the recent shutdown of production in many industries; the initial low supply of products also might contribute to price escalation. During this interim, investors may want to consider investing in commodities and Treasury Inflation-Protected Securities for inflation protection.
As always, it’s best to seek the advice of a professional in this ever-changing environment.
Prospects for Investing in the 2020s
May 1, 2020 · Blog, Financial Planning
⏱ 4 min read
The third decade of the 21st century started out with a vigorous economy, record low unemployment levels, and benign inflation. But late in the first quarter over the span of two weeks, investors faced the fastest stock market correction in history.
With an unpredictable assailant like a global virus, short-term actions by Congress and the Federal Reserve will need time to see if they are effective. Ultimately, the fate of the U.S. and global economies, which in turn will impact the investment markets, is dependent on how long the COVID-19 outbreak continues and if there is a second wave. Clearly, both supply and demand have been dramatically reduced, with a ripple effect on companies, workers, consumers, and investors. Once the crisis has passed, we will learn which sectors, industries, and individual companies remain financially viable with a business model built to sustain this unprecedented economic fallout.
Amid this backdrop, wealth managers must read the tea leaves to anticipate what the investment markets will look like post-coronavirus. The challenge is how to best position assets to take advantage of future gains without giving up ground now and turning paper losses into permanent shortfalls.
For individual investors, it comes down to what you want to accomplish in the next decade – or what your money can accomplish for you. Are you nearing retirement? Will you remain in the accumulation phase, wherein you can afford to take on market risk? Are you just starting out, and are you risk-averse due to the two major economic declines experienced in your relatively short life, or are you prepared to invest in future prospects – wherever they may lie?
Anyone already in or nearing retirement would do well to invest for a steady stream of income. While the DJIA initially took a beating, many blue-chip stalwarts continue to grow and payout dividends as they have long term, through thick and thin. However, pay attention here, as there are some long-standing dividend-paying companies that are starting to suspend or substantially cut dividend payments.
Growth-oriented investors would do well to look at companies that were well-positioned to survive the pandemic, because they may well represent commerce of the future. This includes the well-established FAANG stocks (Facebook, Apple, Amazon, Netflix, and Google), which have become masters of fast and reliable delivery of online content and physical delivery of essential and discretionary products. Unfortunately, the stock prices of these companies have soared in recent years, so it’s time to consider what the “next big thing” in this arena will look like and who are the frontrunners.
With that in mind, take a look at 2020 demographics. Millennials recently surpassed Baby Boomers as the largest generation in the United States, but they aren’t expected to hold this mantle for long. Generation Z/Centennials are on track to enter the workforce in higher numbers during the next decade. This is a generation that has never known life without cell phones and the internet, so expect the technology sector to ramp up not just with consumer innovations, but with ways to help other industries enhance data management, blockchain supply chains, and artificial intelligence – which might become as omnipresent as retail strip malls.
In a post-pandemic world, employers seeking to strengthen their business models might come to embrace the idea of foregoing healthcare and other expensive benefits offered to employees. A subsequent world of higher pay and more public options could spur the growth of entrepreneurship and new small businesses. By taking advantage of remote employees, low overhead expenses, and emerging technologies, smaller companies or conglomerates might be able to compete with the likes of Amazon in both domestic and global markets.
As a short-term precaution, consider how you might defend your portfolio against the possibility of inflation as we stumble out of the pandemic economy. The federal government’s generous stimulus packages combined with a continued easing of monetary policy by the Federal Reserve could lead the United States to higher inflation. This could be exacerbated by the recent shutdown of production in many industries; the initial low supply of products also might contribute to price escalation. During this interim, investors may want to consider investing in commodities and Treasury Inflation-Protected Securities for inflation protection.
As always, it’s best to seek the advice of a professional in this ever-changing environment.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
When it comes to cost accounting, the high-low method is an approach that’s used to break mixed costs into either a variable or fixed cost. Although it’s straightforward, it’s important to do multiple analyses because outlier costs from the available data can sometimes misconstrue operating costs. This calculation occurs by looking at the periods with the most and least activity, as well as the total costs for both the high and low periods.
In order to get results for the high-low method, the variable cost and the fixed cost must be determined first. Once these are established, they are entered into the cost model formula.
Variable Cost is determined as follows:
VC = Highest Activity Cost – Lowest Activity Cost / Highest Activity Units – Lowest Activity Units
The next step is to calculate the Fixed Cost as follows:
FC = Highest Activity Cost – (VC x Highest Activity Units)
Now that the fixed and variable costs are known, the high-low cost can be determined:
High-Low Cost Model = Fixed Cost + (Variable Cost x Unit Activity)
Understanding it Through a Real-World Example
Looking at a furniture manufacturer, it’s good to focus on one product to see how the high-low method works:
The first step is to list production that includes each month, the product produced (let’s say it’s tables), and how much it cost to produce all tables each month. The list could be as follows:
Months
Units Produced
Total Cost ($)
January
153
6,650
February
106
5,653
March
120
6,185
April
126
6,120
May
100
4,888
June
133
6,650
July
113
5,852
August
93
4,988
September
153
6,783
October
166
7,382
November
146
6,783
December
160
7,581
The greatest output or activity for the furniture store happened in October when it produced the highest number of tables: 166 at a cost of $7,382. In August, the furniture store produced the fewest number of tables at 93, manufactured at a cost of $4,988.
Even though the cost may not be the greatest for the peak and valley of production, the corresponding costs for those respective figures is what will be used.
Now that we’ve identified the relevant data, the first task is to determine the variable cost.
VC = Total Cost of High Activity – Total Cost of Low Activity / Highest Activity Unit – Lowest Activity Unit
VC = $7,382 – $4,988 / 166 – 93
VC = $2,394 / 73 = $32.80 per table
Then fixed costs must be calculated:
Total Cost = (VC x Units Produced) + Total Fixed Cost
$7,382 = ($32.80 x 166) + TFC
$7,382 = $5,444.80 + TFC
TFC = $7,382 – $5,444.80 = $1,937.20
It’s important to remember that variable costs are per unit.
Now that we have the total fixed cost, we can then create the total cost equation:
Total Cost = Total Fixed Cost + (VC x Units Produced)
Total Cost = $1,937.20 + ($32.80 x 166) = $7,382
This demonstrates the comprehensive costs for the tables made by the furniture store.
Further Considerations
The high-low method is a quick way to analyze costs. Since it only necessitates the peak and lulls of production data and costs, it can be done more often, along with helping companies plan with limited data to estimate future unit costs.
It’s important to run multiple types of cost analysis because high and low measurements might not give a full picture of costs. Although these two data points may not be the best overall picture of costs a business experiences at those volume levels, it can be an effective measurement until more data becomes available.
Understanding the High-Low Method
May 1, 2020 · Blog, General Business News
⏱ 3 min read
When it comes to cost accounting, the high-low method is an approach that’s used to break mixed costs into either a variable or fixed cost. Although it’s straightforward, it’s important to do multiple analyses because outlier costs from the available data can sometimes misconstrue operating costs. This calculation occurs by looking at the periods with the most and least activity, as well as the total costs for both the high and low periods.
In order to get results for the high-low method, the variable cost and the fixed cost must be determined first. Once these are established, they are entered into the cost model formula.
Variable Cost is determined as follows:
VC = Highest Activity Cost – Lowest Activity Cost / Highest Activity Units – Lowest Activity Units
The next step is to calculate the Fixed Cost as follows:
FC = Highest Activity Cost – (VC x Highest Activity Units)
Now that the fixed and variable costs are known, the high-low cost can be determined:
High-Low Cost Model = Fixed Cost + (Variable Cost x Unit Activity)
Understanding it Through a Real-World Example
Looking at a furniture manufacturer, it’s good to focus on one product to see how the high-low method works:
The first step is to list production that includes each month, the product produced (let’s say it’s tables), and how much it cost to produce all tables each month. The list could be as follows:
Months
Units Produced
Total Cost ($)
January
153
6,650
February
106
5,653
March
120
6,185
April
126
6,120
May
100
4,888
June
133
6,650
July
113
5,852
August
93
4,988
September
153
6,783
October
166
7,382
November
146
6,783
December
160
7,581
The greatest output or activity for the furniture store happened in October when it produced the highest number of tables: 166 at a cost of $7,382. In August, the furniture store produced the fewest number of tables at 93, manufactured at a cost of $4,988.
Even though the cost may not be the greatest for the peak and valley of production, the corresponding costs for those respective figures is what will be used.
Now that we’ve identified the relevant data, the first task is to determine the variable cost.
VC = Total Cost of High Activity – Total Cost of Low Activity / Highest Activity Unit – Lowest Activity Unit
VC = $7,382 – $4,988 / 166 – 93
VC = $2,394 / 73 = $32.80 per table
Then fixed costs must be calculated:
Total Cost = (VC x Units Produced) + Total Fixed Cost
$7,382 = ($32.80 x 166) + TFC
$7,382 = $5,444.80 + TFC
TFC = $7,382 – $5,444.80 = $1,937.20
It’s important to remember that variable costs are per unit.
Now that we have the total fixed cost, we can then create the total cost equation:
Total Cost = Total Fixed Cost + (VC x Units Produced)
Total Cost = $1,937.20 + ($32.80 x 166) = $7,382
This demonstrates the comprehensive costs for the tables made by the furniture store.
Further Considerations
The high-low method is a quick way to analyze costs. Since it only necessitates the peak and lulls of production data and costs, it can be done more often, along with helping companies plan with limited data to estimate future unit costs.
It’s important to run multiple types of cost analysis because high and low measurements might not give a full picture of costs. Although these two data points may not be the best overall picture of costs a business experiences at those volume levels, it can be an effective measurement until more data becomes available.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Coronavirus Aid, Relief and Economic Security Act (HR 748) – This legislation provided $2 trillion of stimulus relief in response to the coronavirus crisis. Provisions of the bill include:
$1,200 for each American making up to $75,000 a year
Additional $600 a week in unemployment benefits for up to four months
$100 billion available for hospitals and health providers; increase Medicare reimbursements for treating COVID-19
$750 million for food banks and food assistance to American Indian reservations, Puerto Rico and other territories
$500 billion in loans or investments to businesses, states, and municipalities
$32 billion in grants to the airline industry
Relief for homeowners with federally backed mortgages
Delay for student loan payments
This bipartisan bill was signed into law by the president on March 27.
Secure 5G and Beyond Act of 2020 (S 893) – Sponsored by Sen. John Cornyn (R-TX), this bill authorizes the development of a strategy to secure and protect next-generation mobile telecommunications (5G) and future generations systems and infrastructure within the United States. These protections should include assistance via mutual defense treaty allies, strategic partners, and other countries to maximize security and operations, as well as protect U.S. competitiveness, consumer privacy and the integrity of regulatory bodies. The bill was introduced on March 27, 2019, and signed into law on March 23, 2020.
Broadband DATA Act (S 1822) – Sen. Roger Wicker (R-MS) introduced this legislation on June 12, 2019, and it was enacted by the president on March 23, 2020. The Act mandates that the Federal Communications Commission (FCC) change the way broadband data is collected, verified, and reported. Going forward, the FCC must collect and distribute broadband maps from wired, fixed-wireless, satellite, and mobile broadband providers by establishing the Broadband Serviceable Location Fabric (a dataset of geocoded information for all broadband service locations) as the centralized vehicle for reporting broadband service availability data.
Supporting Older Americans Act of 2020 (HR 4344) – This bill supports programs relating to care for the elderly, as administered by the Department of Health and Human Services and the Department of Labor. It reauthorizes funding through the fiscal year 2024 for informational services, such as pension counseling; nutritional services, such as meal delivery; disease prevention and health promotion services; community and workforce training for elder care; promotion of independent living and the reduction of social isolation for the elderly; as well as prevention services for abuse and neglect. The bill was introduced by Rep. Suzanne Bonamici (D-OR) on September 16, 2019, and signed into law by the president on March 25, 2020.
Citizenship for Children of Military Members and Civil Servants Act (HR 4803) – This bill was introduced on October 23, 2019, by Rep. Jerrold Nadler (D-NY). In an effort to clarify a rule change initiated by the Trump Administration, this bipartisan legislation guarantees citizenship for anyone born to a U.S. citizen parent stationed overseas, including military members and federal workers. The new law does not apply to children born to non-U.S. citizens stationed overseas working in a role on behalf of the United States.
More Coronavirus Relief, Plus Beefed-Up Security for Technology, the Elderly, and Children Born to U.S. Citizens Serving Overseas
May 1, 2020 · Blog, Congress at Work
⏱ 3 min read
Coronavirus Aid, Relief and Economic Security Act (HR 748) – This legislation provided $2 trillion of stimulus relief in response to the coronavirus crisis. Provisions of the bill include:
$1,200 for each American making up to $75,000 a year
Additional $600 a week in unemployment benefits for up to four months
$100 billion available for hospitals and health providers; increase Medicare reimbursements for treating COVID-19
$750 million for food banks and food assistance to American Indian reservations, Puerto Rico and other territories
$500 billion in loans or investments to businesses, states, and municipalities
$32 billion in grants to the airline industry
Relief for homeowners with federally backed mortgages
Delay for student loan payments
This bipartisan bill was signed into law by the president on March 27.
Secure 5G and Beyond Act of 2020 (S 893) – Sponsored by Sen. John Cornyn (R-TX), this bill authorizes the development of a strategy to secure and protect next-generation mobile telecommunications (5G) and future generations systems and infrastructure within the United States. These protections should include assistance via mutual defense treaty allies, strategic partners, and other countries to maximize security and operations, as well as protect U.S. competitiveness, consumer privacy and the integrity of regulatory bodies. The bill was introduced on March 27, 2019, and signed into law on March 23, 2020.
Broadband DATA Act (S 1822) – Sen. Roger Wicker (R-MS) introduced this legislation on June 12, 2019, and it was enacted by the president on March 23, 2020. The Act mandates that the Federal Communications Commission (FCC) change the way broadband data is collected, verified, and reported. Going forward, the FCC must collect and distribute broadband maps from wired, fixed-wireless, satellite, and mobile broadband providers by establishing the Broadband Serviceable Location Fabric (a dataset of geocoded information for all broadband service locations) as the centralized vehicle for reporting broadband service availability data.
Supporting Older Americans Act of 2020 (HR 4344) – This bill supports programs relating to care for the elderly, as administered by the Department of Health and Human Services and the Department of Labor. It reauthorizes funding through the fiscal year 2024 for informational services, such as pension counseling; nutritional services, such as meal delivery; disease prevention and health promotion services; community and workforce training for elder care; promotion of independent living and the reduction of social isolation for the elderly; as well as prevention services for abuse and neglect. The bill was introduced by Rep. Suzanne Bonamici (D-OR) on September 16, 2019, and signed into law by the president on March 25, 2020.
Citizenship for Children of Military Members and Civil Servants Act (HR 4803) – This bill was introduced on October 23, 2019, by Rep. Jerrold Nadler (D-NY). In an effort to clarify a rule change initiated by the Trump Administration, this bipartisan legislation guarantees citizenship for anyone born to a U.S. citizen parent stationed overseas, including military members and federal workers. The new law does not apply to children born to non-U.S. citizens stationed overseas working in a role on behalf of the United States.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
One of the most important provisions of the CARES Act for small businesses is called the Paycheck Protection Program (PPP). The PPP is a $349 billion program designed to assist small businesses (fewer than 500 employees) facing financial difficulties as a result of the COVID-19 pandemic through specifically structured loans.
The loan program offers funding to cover payroll for up to eight weeks, with the intent of stemming from unemployment. These loans can be forgiven and essentially become a grant if your business meets certain criteria with no need to repay the money.
As the old saying goes, there’s no such thing as a free lunch – or in this case, free government money. There are potential legal risks that could jeopardize the forgivability of the loan.
Conditional Grants
Another way to look at the PPP loans is as conditional grants. The U.S. Small Business Administration (SBA) notes that loans will be forgiven in full if the funds are used for appropriate costs. Covered costs include payroll, mortgage interest, rent, and utilities. Further, the payroll costs must account for at least 75 percent of the loan proceeds used. The employer needs to maintain or quickly rehire employees and maintain wage and salary levels in order to receive 100 percent forgiveness.
The Devil’s in the Certification Details
The loan application process requires certain certifications. Businesses that are still operating need to certify that the current economic uncertainty makes the loan necessary to keep operations going.
If this seems vague, it’s because it is. There probably isn’t a small business out there that is not facing significant uncertainty in the current climate. The problem is that the certification standard the PPP lays out is extremely subjective. As a result, with the encouragement for businesses to apply, many may do so under the impression that they will have their loan fully forgiven to only run into trouble later if they don’t meet the certification standards.
Legal Risks
By not providing any definition about the nature or extent of the required impact to operations that would make the loan request “necessary to support ongoing operations,” the SBA is making both applicants and lenders apprehensive.
Some law firms are even warning clients via their newsletters about potential legal exposure under the False Claims Act (FCA). Legal counsels are cautioning that a misrepresentation included in an application could result in FCA liability. Businesses must navigate between being as aggressive as possible to bolster their application while staying within the rules of the program.
More Certification Guidance is Needed
The government agencies involved need to provide more clear and objective guidance on the conditions needed to meet the certification requirements of the loan application process. Without clear and definable guidance as to what constitutes facing economic uncertainty, small businesses could face problems in the future.
Objective criteria such as a percentage of revenue decline or order capacity would provide a rather bright-line test and give both guidance to businesses and confidence in the process.
Be Right About Free Money: Potential Legal Risks of the Paycheck Protection Loan Program
May 1, 2020 · Blog, Tax and Financial News
⏱ 3 min read
One of the most important provisions of the CARES Act for small businesses is called the Paycheck Protection Program (PPP). The PPP is a $349 billion program designed to assist small businesses (fewer than 500 employees) facing financial difficulties as a result of the COVID-19 pandemic through specifically structured loans.
The loan program offers funding to cover payroll for up to eight weeks, with the intent of stemming from unemployment. These loans can be forgiven and essentially become a grant if your business meets certain criteria with no need to repay the money.
As the old saying goes, there’s no such thing as a free lunch – or in this case, free government money. There are potential legal risks that could jeopardize the forgivability of the loan.
Conditional Grants
Another way to look at the PPP loans is as conditional grants. The U.S. Small Business Administration (SBA) notes that loans will be forgiven in full if the funds are used for appropriate costs. Covered costs include payroll, mortgage interest, rent, and utilities. Further, the payroll costs must account for at least 75 percent of the loan proceeds used. The employer needs to maintain or quickly rehire employees and maintain wage and salary levels in order to receive 100 percent forgiveness.
The Devil’s in the Certification Details
The loan application process requires certain certifications. Businesses that are still operating need to certify that the current economic uncertainty makes the loan necessary to keep operations going.
If this seems vague, it’s because it is. There probably isn’t a small business out there that is not facing significant uncertainty in the current climate. The problem is that the certification standard the PPP lays out is extremely subjective. As a result, with the encouragement for businesses to apply, many may do so under the impression that they will have their loan fully forgiven to only run into trouble later if they don’t meet the certification standards.
Legal Risks
By not providing any definition about the nature or extent of the required impact to operations that would make the loan request “necessary to support ongoing operations,” the SBA is making both applicants and lenders apprehensive.
Some law firms are even warning clients via their newsletters about potential legal exposure under the False Claims Act (FCA). Legal counsels are cautioning that a misrepresentation included in an application could result in FCA liability. Businesses must navigate between being as aggressive as possible to bolster their application while staying within the rules of the program.
More Certification Guidance is Needed
The government agencies involved need to provide more clear and objective guidance on the conditions needed to meet the certification requirements of the loan application process. Without clear and definable guidance as to what constitutes facing economic uncertainty, small businesses could face problems in the future.
Objective criteria such as a percentage of revenue decline or order capacity would provide a rather bright-line test and give both guidance to businesses and confidence in the process.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
So many checks and even more questions! There is a lot of confusion out there over the details surrounding the coronavirus stimulus checks, so below we’ve compiled a list of frequently asked questions and answers.
How much will the check be for? Each adult will receive $1,200; if you filed as married jointly, you’ll get $2,400; with an extra $500 for each qualifying child.
What if I didn’t make any money last year or I was on a reduced income? It doesn’t matter. There is no minimum income threshold you need to pass to qualify. However, if you did not file an income tax return for the 2018 or 2019 tax year, you’ll need to provide your information at the following link so the IRS knows where to send your stimulus money:
I heard that if I make too much money, I won’t receive a check? On the other end of the spectrum, there are income limits based on your tax filing status. If you are single and made more than $75k, married and earned more than $150k, or a head of household with more than $112.5k in adjusted gross income, your stimulus check amount will start to phase-out, and many above these incomes will not receive anything.
My income is under the threshold in 2018 but over in 2019. What are my options? In this case, you can wait to file your 2019 return and qualify to receive the check based on your 2018 tax return. This is easy to do this year given the automatic extensions granted for federal income tax returns.
In 2020, my income is going to be higher than in 2019 and put me above the thresholds. Will I have to pay back my stimulus check? No, there is no claw-back provision in the law, so you won’t have to pay it back.
Is my check taxable? No, it is not taxable income.
I didn’t need to file a tax return in 2018 or 2019 because my only source of income is Social Security Disability Income (SSDI) and my income was limited; do I have to file a return now to get a check? SSDI recipients don’t need to file a return or take additional action. Their checks will be direct deposited or sent via mail – the same way they normally receive their benefits.
I have a child in college who I claim as a dependent. Will either of us get a check? If your child is 18 years or older at the end of the tax year, you aren’t eligible for the $500 check due to his age – even if you claim him as a dependent. Your child likewise won’t get his own check since you claim him as a dependent – even if he works. There is a proposal to change this, but nothing firm currently.
What about a senior parent whom I claim as a dependent? The same rules as above apply, so no. In order to get the $500 check per dependent, the person must both qualify as a dependent and meet the age requirement. Similarly, the senior parent cannot get his own check since you are claiming him as a dependent.
We had a child in 2020. Will I receive a check for this child? Most likely not since the IRS would have no record of your new qualifying dependent based on your 2019 return.
How soon will I receive my check? The government is planning on processing and sending out checks as soon as possible. Based on what the U.S. Treasury has said, as soon as possible means starting to process taxpayer information in April. How soon you’ll receive your money after this depends on whether you’ve set up direct deposit with the government in the current or previous year tax filings. For taxpayers who don’t have direct deposit set up, go here to input your information so the IRS knows where to send your stimulus money:
I heard I can get my stimulus check faster if I pay to have it processed. Is this true? No, and beware because this is a scam. There is no legitimate way to skip to the head of the line.
What happens if I owe the IRS back taxes? The stimulus checks are generally exempt from seizure for existing tax debts. This includes if you are on an installment payment plan to settle a tax bill. The one exception to this possibly could be for child support in arrears.
IRS Source for Non-Filer/Direct Deposit Information:
Answers to Common Questions About the Coronavirus Stimulus Checks
April 14, 2020 · Blog, Guest Post of the Month
⏱ 5 min read
So many checks and even more questions! There is a lot of confusion out there over the details surrounding the coronavirus stimulus checks, so below we’ve compiled a list of frequently asked questions and answers.
How much will the check be for? Each adult will receive $1,200; if you filed as married jointly, you’ll get $2,400; with an extra $500 for each qualifying child.
What if I didn’t make any money last year or I was on a reduced income? It doesn’t matter. There is no minimum income threshold you need to pass to qualify. However, if you did not file an income tax return for the 2018 or 2019 tax year, you’ll need to provide your information at the following link so the IRS knows where to send your stimulus money:
I heard that if I make too much money, I won’t receive a check? On the other end of the spectrum, there are income limits based on your tax filing status. If you are single and made more than $75k, married and earned more than $150k, or a head of household with more than $112.5k in adjusted gross income, your stimulus check amount will start to phase-out, and many above these incomes will not receive anything.
My income is under the threshold in 2018 but over in 2019. What are my options? In this case, you can wait to file your 2019 return and qualify to receive the check based on your 2018 tax return. This is easy to do this year given the automatic extensions granted for federal income tax returns.
In 2020, my income is going to be higher than in 2019 and put me above the thresholds. Will I have to pay back my stimulus check? No, there is no claw-back provision in the law, so you won’t have to pay it back.
Is my check taxable? No, it is not taxable income.
I didn’t need to file a tax return in 2018 or 2019 because my only source of income is Social Security Disability Income (SSDI) and my income was limited; do I have to file a return now to get a check? SSDI recipients don’t need to file a return or take additional action. Their checks will be direct deposited or sent via mail – the same way they normally receive their benefits.
I have a child in college who I claim as a dependent. Will either of us get a check? If your child is 18 years or older at the end of the tax year, you aren’t eligible for the $500 check due to his age – even if you claim him as a dependent. Your child likewise won’t get his own check since you claim him as a dependent – even if he works. There is a proposal to change this, but nothing firm currently.
What about a senior parent whom I claim as a dependent? The same rules as above apply, so no. In order to get the $500 check per dependent, the person must both qualify as a dependent and meet the age requirement. Similarly, the senior parent cannot get his own check since you are claiming him as a dependent.
We had a child in 2020. Will I receive a check for this child? Most likely not since the IRS would have no record of your new qualifying dependent based on your 2019 return.
How soon will I receive my check? The government is planning on processing and sending out checks as soon as possible. Based on what the U.S. Treasury has said, as soon as possible means starting to process taxpayer information in April. How soon you’ll receive your money after this depends on whether you’ve set up direct deposit with the government in the current or previous year tax filings. For taxpayers who don’t have direct deposit set up, go here to input your information so the IRS knows where to send your stimulus money:
I heard I can get my stimulus check faster if I pay to have it processed. Is this true? No, and beware because this is a scam. There is no legitimate way to skip to the head of the line.
What happens if I owe the IRS back taxes? The stimulus checks are generally exempt from seizure for existing tax debts. This includes if you are on an installment payment plan to settle a tax bill. The one exception to this possibly could be for child support in arrears.
IRS Source for Non-Filer/Direct Deposit Information:
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The COVID-19 pandemic has seen a rise in remote working. Even organizations that have always been against it have their employees working from home. With some areas experiencing complete lockdowns, this means you find yourself in an unfamiliar work environment.
Remote working means that you have to work outside a traditional office environment. Although some people already have experience working remotely, there are a good number of workers who might have a hard time getting anything done from home. This is particularly true for those with a family that includes young children.
But with the current epidemic, many don’t have much choice other than to agree with the concept that work doesn’t have to be done in a specific place to be performed successfully. Your employer may have already set a work-at-home policy, but how do you ensure you are productive? Here are a few tips to help you retain your employment.
Create a Workspace
If you don’t already have a home office, then it’s time to be resourceful and create a workspace. Unfortunately, since this is unplanned, you might not have an ergonomically friendly work area. This means you could hurt yourself while working; for example, sitting too long in an uncomfortable position. But think outside the box and utilize what you have, such as using pillows to create a comfortable posture. Also, ensure you take frequent breaks.
Don’t forget to choose a space with minimal distractions.
Establish a Routine and Stick to It
The fact that you no longer have to wake up early to get to the office might tempt you to sleep more. It is important to have a work mindset. To achieve a sense of normalcy that you were used to in the office, you need to plan a schedule for your work hours and stick to it. Failure to create a work routine may find you wasting work hours.
Remember, if you live with family or friends, let them know your work hours and have them respect that.
Be Flexible
It’s important that you be flexible, especially if you have kids in the house. This makes it hard to work a 9 to 5 job. A lockdown means you probably do not have someone to come over and help with chores or childcare. The way out is to experiment with different plans. Try working late at night, early in the morning or when your children take a nap.
Use Time Management Apps
Your employer already set goals and roles for you. But achieving them while working at home is challenging. Use time management apps to track the amount spent working on tasks. Such apps, whether web or mobile-based, can help minimize distractions.
Avoid Social Media
There is so much information on the coronavirus pandemic and there is a need to stay updated. But this can turn out to be a distraction that causes you to miss out on work time. Set a time to check such updates and stick to it.
Informal Communication Groups
Apart from official online meetings or discussions, it’s good to keep in touch with colleagues. If your company did not set up such meetings, then you should. There are many communication tools available today that you can use. Keep in mind, isolation can lead to depression, especially if you live alone and are used to an active social life.
Work-Life Balance
Don’t spend all of your day working. Set daily tasks and stick with them. Set a time to exercise; it’s good for productivity and helps you avoid getting sore, which will generally affect your health. Log off from your work and do a different activity.
Use Secure Connections
Cybercriminals are now more likely to target remote workers. There are already reported cases of coronavirus ransomware and malware. This not only affects your work but can put your company at risk. Ensure that you use a secure wifi and virtual private network (VPN). Most importantly, don’t ignore your company’s security policies just because you are working from home.
Final Thoughts
There is a lot of debate surrounding remote working. Employers may see the benefit of remote working and adopt it more. Whether this will be the case, only time will tell. But we should brace for unexpected changes in the workplace when things finally get back to normal.
The most important thing right now is to keep in mind that your productivity will depend on your self-discipline, time-management skills, technology skills (to use new apps) and adaptability.
New to Remote Working? Here are Some Tips for Staying Productive
April 1, 2020 · Blog, What's New in Technology
⏱ 4 min read
The COVID-19 pandemic has seen a rise in remote working. Even organizations that have always been against it have their employees working from home. With some areas experiencing complete lockdowns, this means you find yourself in an unfamiliar work environment.
Remote working means that you have to work outside a traditional office environment. Although some people already have experience working remotely, there are a good number of workers who might have a hard time getting anything done from home. This is particularly true for those with a family that includes young children.
But with the current epidemic, many don’t have much choice other than to agree with the concept that work doesn’t have to be done in a specific place to be performed successfully. Your employer may have already set a work-at-home policy, but how do you ensure you are productive? Here are a few tips to help you retain your employment.
Create a Workspace
If you don’t already have a home office, then it’s time to be resourceful and create a workspace. Unfortunately, since this is unplanned, you might not have an ergonomically friendly work area. This means you could hurt yourself while working; for example, sitting too long in an uncomfortable position. But think outside the box and utilize what you have, such as using pillows to create a comfortable posture. Also, ensure you take frequent breaks.
Don’t forget to choose a space with minimal distractions.
Establish a Routine and Stick to It
The fact that you no longer have to wake up early to get to the office might tempt you to sleep more. It is important to have a work mindset. To achieve a sense of normalcy that you were used to in the office, you need to plan a schedule for your work hours and stick to it. Failure to create a work routine may find you wasting work hours.
Remember, if you live with family or friends, let them know your work hours and have them respect that.
Be Flexible
It’s important that you be flexible, especially if you have kids in the house. This makes it hard to work a 9 to 5 job. A lockdown means you probably do not have someone to come over and help with chores or childcare. The way out is to experiment with different plans. Try working late at night, early in the morning or when your children take a nap.
Use Time Management Apps
Your employer already set goals and roles for you. But achieving them while working at home is challenging. Use time management apps to track the amount spent working on tasks. Such apps, whether web or mobile-based, can help minimize distractions.
Avoid Social Media
There is so much information on the coronavirus pandemic and there is a need to stay updated. But this can turn out to be a distraction that causes you to miss out on work time. Set a time to check such updates and stick to it.
Informal Communication Groups
Apart from official online meetings or discussions, it’s good to keep in touch with colleagues. If your company did not set up such meetings, then you should. There are many communication tools available today that you can use. Keep in mind, isolation can lead to depression, especially if you live alone and are used to an active social life.
Work-Life Balance
Don’t spend all of your day working. Set daily tasks and stick with them. Set a time to exercise; it’s good for productivity and helps you avoid getting sore, which will generally affect your health. Log off from your work and do a different activity.
Use Secure Connections
Cybercriminals are now more likely to target remote workers. There are already reported cases of coronavirus ransomware and malware. This not only affects your work but can put your company at risk. Ensure that you use a secure wifi and virtual private network (VPN). Most importantly, don’t ignore your company’s security policies just because you are working from home.
Final Thoughts
There is a lot of debate surrounding remote working. Employers may see the benefit of remote working and adopt it more. Whether this will be the case, only time will tell. But we should brace for unexpected changes in the workplace when things finally get back to normal.
The most important thing right now is to keep in mind that your productivity will depend on your self-discipline, time-management skills, technology skills (to use new apps) and adaptability.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.



 With the coronavirus spreading across the globe, catching individuals and governments off guard, business owners have not fared any better. While the virus is having a grave impact on the health of millions across the globe, businesses have seen an equally serious impact on their bottom line. The virus is projected to hit businesses’ cash-flow and the ability to stay open post-pandemic.
 Since the escalation of COVID-19 cases, malicious activity from cybercriminals is also on the rise.
 During the government shutdown as a result of COVID-19, sadly, millions have lost their jobs. However, there is a silver lining: there are some industries that, because of the shutdown, are actually hiring. Here are a few leads to help those who might have been affected.
 The third decade of the 21st century started out with a vigorous economy, record low unemployment levels, and benign inflation. But late in the first quarter over the span of two weeks, investors faced the fastest stock market correction in history.
 When it comes to cost accounting, the high-low method is an approach that’s used to break mixed costs into either a variable or fixed cost. Although it’s straightforward, it’s important to do multiple analyses because outlier costs from the available data can sometimes misconstrue operating costs. This calculation occurs by looking at the periods with the most and least activity, as well as the total costs for both the high and low periods.
 Coronavirus Aid, Relief and Economic Security Act (HR 748) – This legislation provided $2 trillion of stimulus relief in response to the coronavirus crisis. Provisions of the bill include:
 One of the most important provisions of the CARES Act for small businesses is called the Paycheck Protection Program (PPP). The PPP is a $349 billion program designed to assist small businesses (fewer than 500 employees) facing financial difficulties as a result of the COVID-19 pandemic through specifically structured loans.
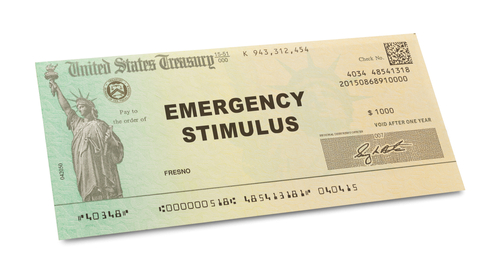
 The COVID-19 pandemic has seen a rise in remote working. Even organizations that have always been against it have their employees working from home. With some areas experiencing complete lockdowns, this means you find yourself in an unfamiliar work environment.